

Business Operation · 2025
In this section22 topics
- Corporate Information4 items
- Dividend Policy2 items
- Major Shareholders1 item
- Business Strategies Overview7 items
- Material Changes & Developments1 item
- Use of Proceeds from Securities Offerings1 item
- Commitments Made in the Registration Statement1 item
- Group Operating-Structure Policy1 item
- Companies Where the Company Holds ≥10%1 item
- Shareholders with Potential Conflict of Interest1 item
- Relationships Among Major Shareholders2 items
- Shareholders' Agreement1 item
- Shareholding Diagram (Group Structure)2 items
- Income Structure4 items
- Product / Service Characteristics3 items
- Research & Development3 items
- Assets Used in the Business6 items
- Marketing Policy & Competition3 items
- Procurement of Products & Services2 items
- Projects Under Construction1 item
- Debentures & Bills of Exchange1 item
- Convertible Securities1 item
Corporate Information
Company Name
Regional Container Lines Public Company Limited
Telephone
0-2296-1096, 0-2296-1093
Website
http://www.rclgroup.com
company.secretary@rclgroup.com
Dividend Policy
Dividend Policy
The Company has set the policy to pay dividend to the shareholders at the rate of not exceeding 50% of the consolidated net earnings, upon obtaining approval from the shareholders based on majority votes at general meetings. The Board of Directors may declare interim dividend to the shareholders from time to time if the Board opines that the earnings of the Company justify such payment. The dividend payout, when made, shall be reported to the shareholders at the next general meeting.
Historical Dividend Payments
| This Year | Last Year | 2 Years Ago | 3 Years Ago | 4 Years Ago | Metric | Description | Remark |
|---|---|---|---|---|---|---|---|
| 9.85 | 11.07 | 1.81 | 29.71 | 21.69 | Net profit per share (Baht : Share) | Net profit per share (baht : share) | |
| 2.5 | 2.5 | 0.75 | 7 | 6 | Dividend per share (Baht : Share) | Dividend per share (baht : share) | The Company had already declared and made two interim dividend payments during the year 2025 on 5 September 2025 at Baht 0.50 per share and on 4 December 2025 at Baht 0.50 per share. The remaining dividend will be paid at the rate of Baht 1.50 per share and must be approved by the shareholders at the Annual General Meeting of Shareholders on 17 April 2026. |
| 0 | 0 | 0 | 0 | 0 | Dividend stock ratio (Number of original shares: dividend shares) | Ratio of stock dividend payment (existing share : stock dividend) | |
| 0 | 0 | 0 | 0 | 0 | Dividend share value per share (Baht : Share) | Value of stock dividend per share (baht : share) | |
| 2.5 | 2.5 | 0.75 | 7 | 6 | Total dividend payment value (Baht : Share) | Total dividend payment (baht : share) | |
| 25.38 | 22.58 | 41.44 | 23.56 | 27.66 | Dividend payout ratio to net profit (%) | Dividend payout ratio compared to net profit (%) |
Business Strategies Overview
Introduction
RCL Group is committed to continuously enhancing its position as a leading asset-based regional transportation provider with emphasis on meeting the expectations of its customers and shareholders through the dedication of the management and staff. In addition to promoting its competencies with up-to-date techniques and resources, the Group embraces its 5 core values introduced in 2011, namely Accountability, Teamwork, Result Orientation, Customer Focus and Leadership with Integrity, to achieve this mission.
The Group’s vision is “A trusted and reliable regional container carrier and logistics provider committed to quality, sustainability, efficiency and innovations”.
Chairman's Message
Dear Shareholders,
2025 marked another challenging year for the container shipping industry, amid heightened volatility in the global economy, escalating geopolitical tensions, and persistent uncertainty in supply and demand dynamics. Nevertheless, Regional Container Lines Public Company Limited (“the Company” or “RCL”) was able to maintain stable operations through prudent and disciplined strategic management. On behalf of the Board of Directors and the Management, I am pleased to inform our shareholders and stakeholders of the key operational developments that enabled the Company to maintain its business strength over the past year.
Industry Environment and Challenges
During the year, the container shipping industry continued to face pressure from excess capacity, a gradual recovery in demand, and significant volatility in freight rates. These conditions were largely influenced by geopolitical conflicts across various regions, particularly the tension in the Red Sea, which resulted in longer voyage times, higher operating costs, and disruptions to the balance of the global logistics system. Meanwhile, uncertainty surrounding international trade policies remained a critical factor that industry operators closely monitored.
Growth Strategy and Service Enhancement
The Company continued to expand collaboration with logistics partners to strengthen its integrated service network, while upgrading its fleet systematically through investments in new and efficient vessels suited to specific trade routes. In parallel, older vessels with longer service lives were divested during periods of heightened demand in the vessel market. The Company also expanded its service network into new high-potential markets, such as Latin America, while maintaining a strong customer-centric approach to continuously enhance service quality and customer experience.
Sustainability, Technology, and ESG
The Company operates under a framework of sustainable development and good corporate governance (ESG), with a strong focus on minimizing environmental impact through initiatives such as the installation of pollution-reduction equipment, the implementation of sustainability projects, and collaboration in the development and promotion of biofuel usage within the maritime transport industry. In addition, the Company invests in digital technologies, data management, and automation systems to enhance operational efficiency and agility. Moreover, the Company places strong emphasis on human capital development, talent retention, and career advancement opportunities to support long-term organizational growth. In 2025, the Company also declared its intention to join the Thai Private Sector Collective Action Against Corruption (CAC), reflecting its commitment to conducting business with transparency and strong corporate governance.
Recognition and Achievements
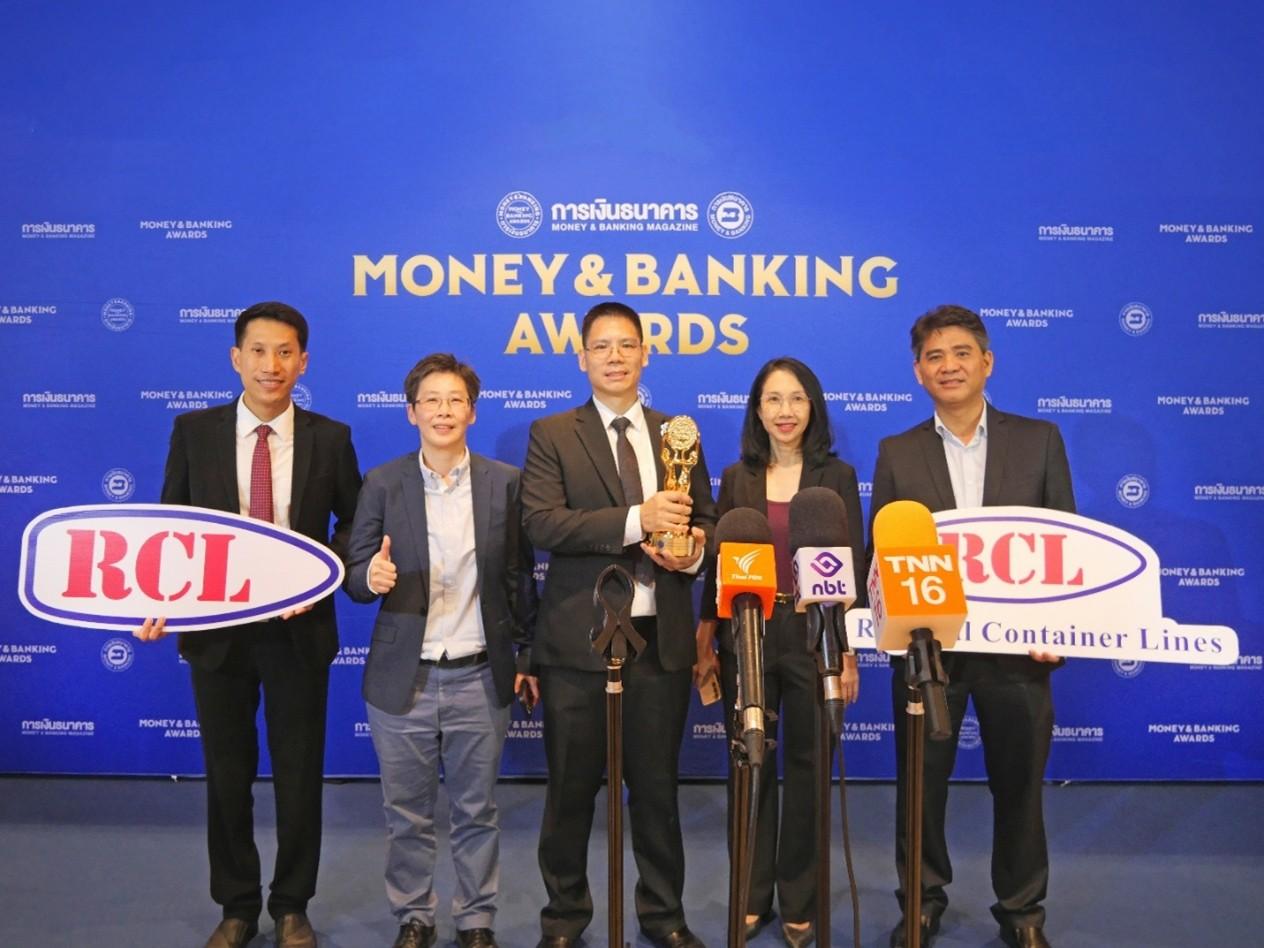
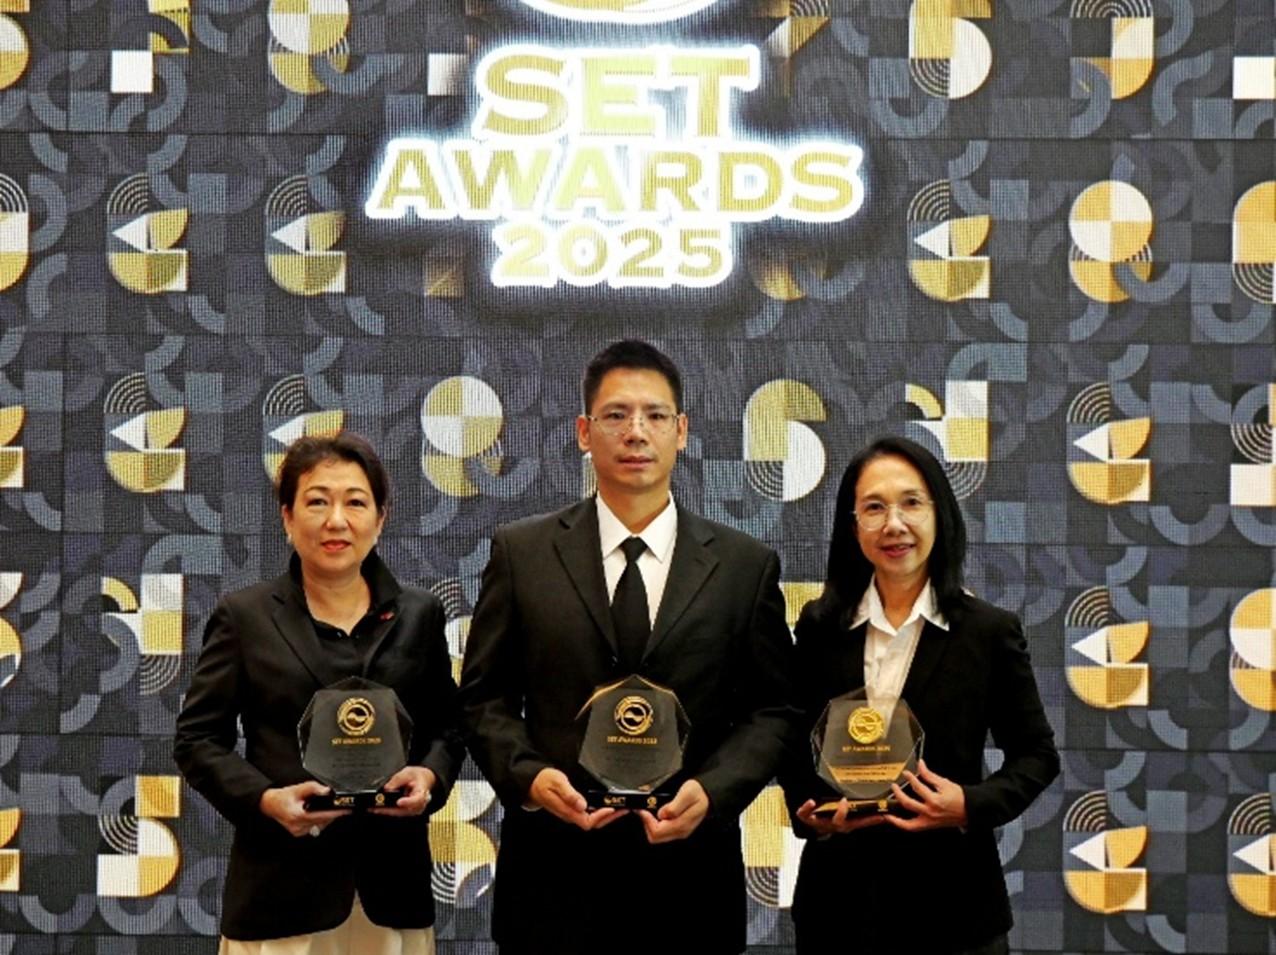
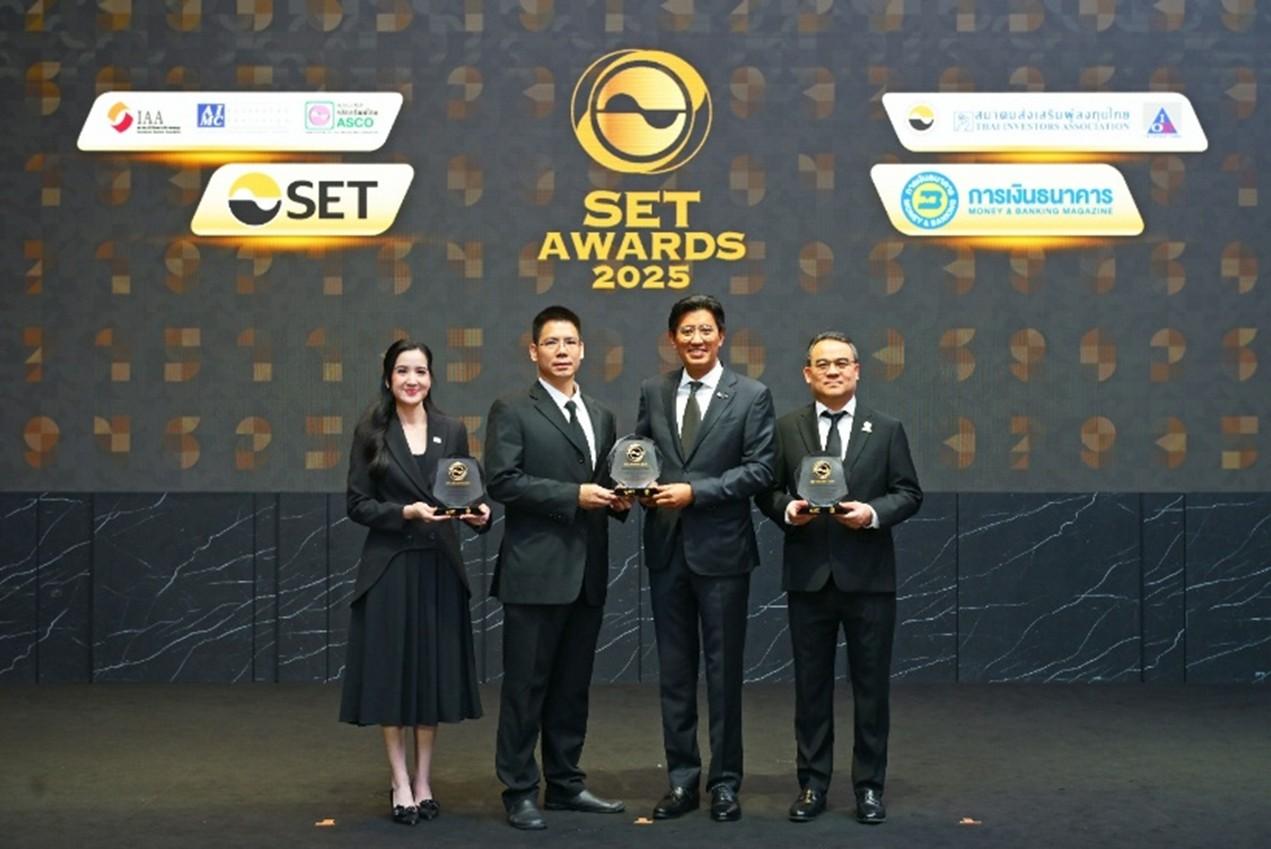
In recognition of its commitment to responsible and sustainable business practices, the Company received the Best Public Company of the Year award in the Transportation and Logistics category at the Money & Banking Awards 2025. The Company was also honored with three awards at the SET Awards 2025, namely the Outstanding Company Performance Award, the Outstanding CEO Award, and the Outstanding Young Rising Star CEO Award, underscoring excellence in performance, leadership, and sustainable organizational development.
Finally, on behalf of the Board of Directors, I would like to express my sincere appreciation to our shareholders, customers, business partners, employees, and all stakeholders for their continued trust and support. The Company remains firmly committed to conducting its business with transparency, responsibility, and sustainability over the long term.
-signed-
(Dr. Jamlong Atikul)
Chairman of the Board of Directors
Regional Container Lines Public Company Limited
Vision
A trusted and reliable regional container carrier and logistics provider committed to quality, sustainability, efficiency and innovations.
Objectives
1. To be trusted as a reliable Asian container carrier and logistic service provider
2. To positively contribute to our environment and society
3. To strengthen our liner and feeder service network to create an accessibility of trade to the different parts of Asia, India ISC and Mideast.
4. To provide a swift and utmost quality of service to our customers
5. To closely work with our business partners to expand our service and reach to our new and existing customers
6. To Digitize our tools, processes, enhance situation awareness to be an efficient service provider (CP)
7. To be a container shipping specialized assistant to our customers
8. To provide the value-added logistics solutions to meet the customer demand.
Goals
The Group’s goal is to uphold its leadership position amongst the containerized shipping operators focusing on the inter-Asia regional trades. RCL’s geographical business coverage includes North East Asia, South East Asia, Indian Sub-continent, South Asia, the Middle East, the Red Sea, and East Africa.
Business Strategies
The Group's core strategies focus on rejuvenating the fleet, expanding business opportunities into new markets, prioritizing customer engagement, and promoting environmental awareness to drive sustainable growth and strengthen market competitiveness. The Group is committed to continuously developing fleet capabilities by investing in high-efficiency vessels equipped with modern, eco-friendly technologies to improve operational performance, reduce greenhouse gas emissions, and lower maintenance costs. At the same time, the Group has expanded its services into high-potential and continuously growing markets, such as the Indian subcontinent, the Middle East, East Africa, and Latin America. Additionally, the Group emphasizes strengthening customer engagement by improving services through the development of various systems to enhance the customer experience and ensure maximum satisfaction. The Group also conducts its business with a strong focus on environmental responsibility, demonstrating a commitment to reducing its environmental impact. Initiatives include disposing old vessels and replacing them with new, fuel-efficient vessels capable of supporting alternative fuels, while ensuring compliance with regulations set by the International Maritime Organization (IMO).
Other Information
| Name | Description |
|---|---|
| Success | At ended 2025, the Group is currently ranked 22nd (ranked 22nd in 2025 and 23rd in 2024) amongst the world container shipping operators and recognized as amongst the top regional operators by leading industrial publications. As of December 31, 2025, the Group operates a total of 46 vessels with a combined carrying capacity of 153,745 TEUs. This expansion has enhanced service efficiency. In 2025, the Company ordered two additional new-built 14,000 TEUs vessels with a leading shipyard in the Republic of Korea. These vessels will be the largest vessels in the Company’s fleet, scheduled for delivery within 2028, with the objectives of enhancing fleet efficiency, supporting customer demand, and complying with environmental standards, thereby laying a solid foundation for sustainable growth. The following are key factors in supporting the Group’s performance and achievements; • Maintaining its position as a key regional carrier, • Enhanced presence in the regional trades it serves, • Loyal and large diverse customer base support, • Strong customer-oriented business units ensuring customer expectations are met, • Competent and motivated management, staff and vessel crew to deliver high-quality of services to the customers, • Complementing business strategy between Shipper-Owned-Container (SOC) and Carrier-Owned-Container activities (COC), • Comprehensive and effective service network, • Competitive and conscious operating cost structure. Furthermore, the Group is aware of the importance of sustainable development and is committed to conducting business responsibly towards the environment and society in the areas where the Group operates. This involves considering negative impacts on the environment and society and creating positive impacts for stakeholders involved in the Group's business operations. The Group is dedicated to sustainable business practices and creating value for society and the environment while growing its business. |
| Awards | Regional Container Lines Public Company Limited (RCL) is proud to have received prestigious recognition for its outstanding performance and leadership during 2025. 1. 2025 Public Company of the Year Award (Transportation and Logistics Category) – Money & Banking Awards 2025 The awards were presented to companies listed on the Stock Exchange of Thailand (SET) that demonstrate exceptional overall performance throughout the year by Money & Banking magazine.
2. SET Awards 2025 In 2025, RCL received three distinguished awards at the SET Awards 2025 for its excellence in company performance and leadership. Business Excellence Awards 2.1. Outstanding Company Performance Award (market capitalization of over THB 10 billion but not exceeding THB 30 billion) This award recognizes the company’s robust operational performance, prudent financial management, strong adherence to corporate governance standards, and sustained ability to deliver stable business results.
Best CEO Awards 2.2 Outstanding CEO Awards 2.3 Outstanding Young Rising Star CEO Award Dr. Twinchok Tanthuwanit, President of RCL, received two awards recognizing top executives who have led their organizations to success across multiple dimensions, upholding the principles of good corporate governance in organizational management, demonstrating strategic vision and capabilities, dedication to investor relations activities, as well as emphasis on social responsibility and steadfast support for creating sustainability in business operations.
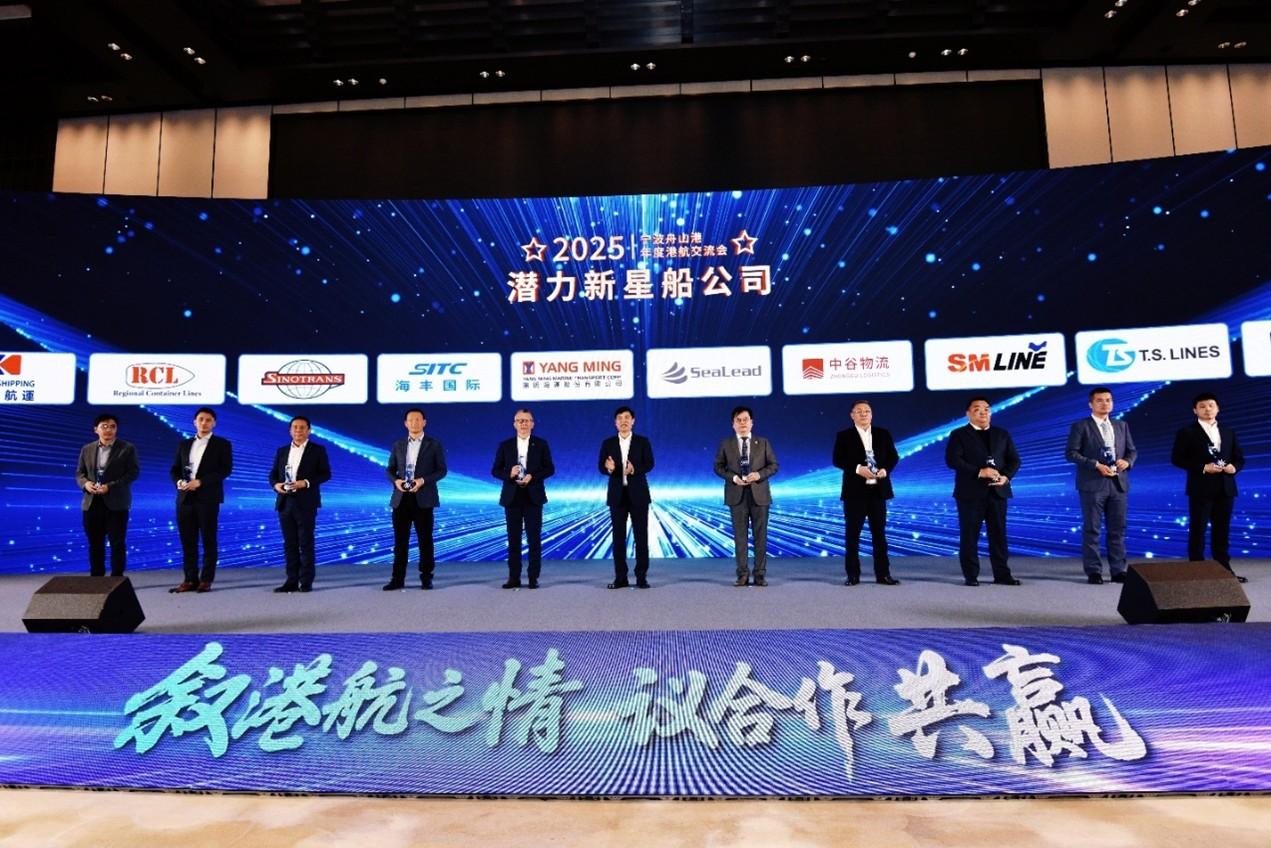
3. Quality Person of the Year 2025 (Business Sector - Transportation and Logistics) , Foundation of Science and Technology Council of Thailand (FSTT) Dr. Twinchok Tanthuwanit was honored with the Quality Person of the Year 2025 award in the Business Sector – Transportation and Logistics category for his outstanding professional achievements and dedication to activities that benefit society and the nation. 4. The Most Promising Shipping Company 2025 – Ningbo Port Group RCL Ningbo Branch has been honored as the Most Promising Shipping Company 2025 by Ningbo Port Group. In recognition of its outstanding performance in developing hinterland businesses, including the Yangtze River region, northern and southern Zhejiang, and sea-rail intermodal transport.
5. Excellent Shipping Partner – Yiwu Port RCL Ningbo Branch has been awarded the title of Excellent Shipping Partner in 2025. This honor is in recognition of RCL’s milestone in establishing the Yiwu Sales Office in 2025, as well as its new initiatives, including the Yiwu CCA railway service and other key projects.
|
| Core Value | A - Accountability T - Teamwork R - Result Orientation C - Customer Focus (external and internal) L - Leadership with Integrity
|
Material Changes & Developments
Material Changes & Developments
| Year | Description |
|---|---|
| 2,022 |
|
| 2,023 | • Incorporated RCL Shipping LLC (“RCL Shipping”) with a registered capital of AED 735,000 by holding 60% shares through RCF in order to expand its business and marine shipping services to the Middle East. • Expanded the business of reefer container to support customer’s need. • Organized naming ceremony for the 1,930 TEUs, namely Nattha Bhum which is the largest Bangkok Max size vessel that can enter the Chao Phraya River. It also has advanced technology that complies with IMO and the sustainability policy of the Company. • Received the Best Company of the Year 2023 Award – Service Industry from Money and Banking Awards 2023 two years in a row which reflected continuously efficient operations of the Group. • Received Outstanding Company Performance Awards – Business Excellence from SET Award 2023. This award is given to companies with outstanding performance in term of business performance, good corporate governance and compliance with the SET regulations. • Improved and expanded the Company’s fleet. As of 31st December 2023, the Company has owned and operated 41 vessels with a capacity of 107,708 TEUs, increase from last year, which enhances service efficiency, response to customer’s demand and drive the Group to the success. |
| 2,024 | • Five new vessels have been added to the Company’s fleet, including two 12,000 TEUs vessels – Varanya Bhum and Ussama Bhum, and three 7,000 TEUs vessels – Guru Bhum, Hemma Bhum, and Itti Bhum. This expansion has strengthened the Company’s ability to maintain continuous profitability from fleet utilization while supporting the growing and diverse demands of the customers. • The Company has strategically expanded into high-potential markets, such as India, the Middle East, and East Africa, diversifying its service routes and enhancing operational capacity. Additionally, the Company has increased its reefer container services to better meet diverse customer needs and adapt to rapidly changing and growing market demands. • RCL achieved a global ranking of 22nd among leading ocean freight service providers and remains among the top container shipping operators in the region, as recognized by leading industry publications. As of December 31, 2024, RCL operates 46 vessels with a total carrying capacity of 151,519 TEUs. |
| 2,025 | • Established RCL Logistics (Hong Kong) Limited and RCL Logistics (Vietnam) Co., Ltd. to conduct international trading operations and expand the Group’s logistics-related service businesses. • Established four subsidiary companies to manage vessel operations, namely Gavee Bhum Pte. Ltd., Hathaya Bhum Pte. Ltd., Kema Bhum Pte. Ltd., and Laticha Bhum Pte. Ltd. • Entered into a collaboration to advance the use of biofuels in the maritime transportation industry. The Company conducted its first bunkering of B24 VLSFO, one of the cleaner fuel alternatives for cargo vessels, for the vessel Piya Bhum in the Company’s fleet in October 2025. This initiative reflects the Company’s commitment to reducing carbon emissions and driving sustainable growth. • Received the Best Public Company of the Year award in the Transportation and Logistics category at the Money & Banking Awards 2025, as well as three awards at the SET Awards 2025, namely the Outstanding Company Performance Award, Outstanding CEO Award, and Outstanding Young Rising Star CEO Award. • Placed an order for two new 14,000 TEU vessels, the largest vessels in the Group’s fleet, with HD Hyundai Heavy Industries Co., Ltd. of South Korea, a global leader in the shipbuilding industry. |
Use of Proceeds from Securities Offerings
Is There Money Raised from a Securities Offering Still to Report On?
No
Commitments Made in the Registration Statement
Are There Commitments or Conditions from an Offering or Listing?
No
Group Operating-Structure Policy
Description
The Group has organized its operations in accordance with a defined structure to ensure efficient management and alignment with its business strategy. As of 31 December 2025, the Group’s operational structure is as follows.
Companies Where the Company Holds ≥10%
Companies (≥10% Holding)
| Company Name | Address | Province | Zip Code | Telephone | Fax | Business Type | Security Type | Shares | Paid-up Shares |
|---|---|---|---|---|---|---|---|---|---|
| RCL Investment Pte. Ltd. | 11 Keppel Road, 8th Fl., ABI Plaza, Singapore 089057 | (65) 6220 0388 | (65) 6221 9760 | Holding company | Common shares | 10,000,000 | 10,000,000 | ||
| Regional Container Lines Pte. Ltd. | 11 Keppel Road, 8th Fl., ABI Plaza, Singapore 089057 | (65) 6220 0388 | (65) 6221 9760 | Ship owning and operating | Common shares | 136,502,572 | 136,502,572 | ||
| RCL Shipmanagement Pte. Ltd. | 11 Keppel Road, 8th Fl., ABI Plaza, Singapore 089057 | (65) 6220 0388, 6221 7488 | (65) 6221 9727 | Ship management | Common shares | 300,000 | 300,000 | ||
| RCL Feeder Pte. Ltd. | 11 Keppel Road, 8th Fl., ABI Plaza, Singapore 089057 | (65) 6220 0388 | (65) 6221 9760 | Holding company, cargo consolidation and operating | Common shares | 146,850,000 | 146,850,000 | ||
| Regional Container Lines (H.K.) Ltd. | 11th Fl., No. 9 Des Voeux Road West, Hong Kong | (852) 2526 3318 | (852) 2537 5456 | Holding company, shipping agent and the provision of transportation and cargo handling services | Common shares | 45,000,000 | 45,000,000 | ||
| Regional Container Lines Shipping Co., Ltd. | Room 2601-2603, Harbour Ring Plaza, No.18, Xi Zang Middle Road, Shanghai, China | (8621) 6132 4500 | (8621) 6132 4505 | Shipping agent and broker | Common shares | 1,840,000 | 1,840,000 | ||
| RCLS Co., Ltd. | 16th Fl., Panjathani Tower Bldg.,127/21 Nonsi Road (Ratchadapisek Road), Chongnonsi, Yannawa, Bangkok, Thailand | Bangkok | 10120 | (662) 296 1096 | (662) 296 1098 | International Business Center for the Group | Common shares | 5,000,000 | 5,000,000 |
| RCL Logistics Co., Ltd. | 14th Fl., Panjathani Tower Bldg., 127/18 Nonsi Road (Ratchadapisek Road), Chongnonsi, Yannawa, Bangkok, Thailand | (662) 296 1284-6 | (662) 296 1279 | Logistics services | Common shares | 500,000 | 500,000 | ||
| RCL Agencies (M) Sdn. Bhd. | Suite 6.02, Level 6 IMS 2, 88 Jalan Batai Laut 4, Taman Intan, 41300 Klang Selangor, Malaysia | (603) 86810570 | Shipping agent | Common shares | 500,000 | 500,000 | |||
| Regional Logistics Co., Ltd. | Room 2604, Harbour Ring Plaza, No.18, Xi Zang Middle Road, Shanghai, China | (8621) 6132 4500 | (8621) 6132 4505 | Logistics Services | Common shares | 170,000 | 170,000 | ||
| RCL (Myanmar) Company Limited | #11-01, No. 422/426, Corner of Strand Road and Botahtaung Pagoda Road, Botahtaung Township, Yangon, Myanmar | (95-1)202065/(95-1)-202067/ (95-1)202103 | Shipping Agent | Common shares | 250,000 | 250,000 | |||
| Santi Bhum Co., Ltd. | 30th Fl., Panjathani Tower Bldg., 127/35 Nonsi Road (Ratchadapisek Road), Chongnonsi, Yannawa, Bangkok, Thailand | Bangkok | 10120 | (662) 296 1096 | (662) 296 1098 | Ship owning and operating | Common shares | 480,000 | 480,000 |
| Thitti Bhum Co., Ltd. | 30th Fl., Panjathani Tower Bldg., 127/35 Nonsi Road (Ratchadapisek Road), Chongnonsi, Yannawa, Bangkok, Thailand | Bangkok | 10120 | (662) 296 1096 | (662) 296 1098 | Ship owning and operating | Common shares | 480,000 | 480,000 |
| TIPS Co., Ltd. | 112/2 Moo. 3, Thung Sukhla Subdistrict, Si Racha District, Chon Buri, Thailand | Chonburi | 20230 | 66 38 408 400 | 66 38 408 433 | Terminal operating | Common shares | 1,000,000 | 1,000,000 |
Income Structure
Introduction
Breakdown of 2025 Revenues
In 2025, the Group’s revenue continued to be principally generated from freight income arising from its container shipping operations, supported by two core operating modes: Carrier-Owned Container (COC) and Shipper-Owned Container (SOC) activities. In addition to the carriage itself, the Group’s revenue model reflects the broader service value chain, incorporating freight-related charges and recoveries, documentation-related charges, and operational and logistics solutions, including special equipment solutions as well as slot and charter-related offerings.
During the year, commercial execution remained focused on disciplined capacity and asset utilization, with measures directed at aligning resources to demand conditions and supporting service delivery. Operational levers referenced in internal business discussions included calibrated overbooking in selected clusters, and container management actions such as maintaining leasing arrangements and prioritizing free-use containers to preserve equipment availability and mitigate long-stay exposure.
The operating environment in 2025 remained dynamic, shaped by factors such as port congestion and vessel delays, changes in cost structures, and demand swings linked to trade policy developments. In response, the Group maintained an emphasis on active capacity management, including service optimization, cost discipline, and cargo mix enhancement. In parallel, management continued to progress digital and AI-enabled initiatives intended to support operational efficiency and scalable execution, including programs referenced internally for knowledge management and customer communication handling.
Income Classified by Nature of Activities
In 2025, COC services accounted for 75% of the total volume, around 82% of the total freight income for the whole RCL Group. SOC accounted for 25% of volume, with 18% of freight income.
Breakdown of Total Income by Geographical Location
Freight income | 2025 ฿million | % | 2024 ฿million | % | 2023 ฿million | % | 2023 ฿million | % | 2021 ฿million | % |
Thailand | 4,287 | 11.61 | 3,710 | 10.57 | 4,042 | 15.39 | 5,318 | 10.21 | 2,476 | 6.52 |
Singapore | 41,034 | 111.13 | 36,537 | 104.10 | 28,055 | 106.80 | 58,043 | 111.47 | 39,492 | 103.99 |
Hong Kong | 28 | 0.08 | 34 | 0.10 | 25 | 0.10 | 74 | 0.14 | 92 | 0.24 |
(Elimination of inter-company transactions) | -8,425 | -22.82 | -5,184 | -14.77 | -5,854 | -22.29 | -11,361 | -21.82 | -4,081 | -10.75 |
Total Freight Income | 36,924 | 100 | 35,096 | 100 | 26,268 | 100 | 52,074 | 100 | 37,979 | 100 |
Breakdown of Total Income by the Company and its Subsidiaries
Freight income | 2568 | 2567 | 2566 | 2565 | 2564 |
Regional Container Lines Public Company Limited | ฿million 2,359 | ฿million 1,640 | ฿million 2,278 | ฿million 4,847 | ฿million 2,114 |
Subsidiary companies operating in Thailand | ฿million | ฿million | ฿million | ฿million | ฿million |
| 394 | 414 | 254 | 342 | 362 |
| 767 | 828 | 811 | 129 | - |
| 767 | 828 | 699 | - | - |
Subsidiary companies operating in Singapore | US$ million | US$ million | US$ million | US$ million | US$ million |
| 263.5 | 140.9 | 146.3 | 214.6 | 85.9 |
| 982.1 | 888.8 | 654.8 | 1,431.4 | 1,139.0 |
Subsidiary company operating in Hong Kong | HK$ million | HK$ million | HK$ million | HK$ million | HK$ million |
| 5.4 | 7.4 | 5.8 | 16.6 | 22.3 |
| 1.2 | - | - | - | - |
Product / Service Income
| Category | Description | This Year | This Year % | Last Year | Last Year % | 2 Years Ago | 2 Years Ago % |
|---|---|---|---|---|---|---|---|
| Total revenue from operations | Total revenue from operations | 37,818,188 | 100 | 37,250,093 | 100 | 27,136,995 | 100 |
| Freight Income | 36,923,567 | 97.63 | 35,095,921 | 94.22 | 26,267,560 | 96.8 | |
| Other | Others | 894,621 | 2.37 | 2,154,172 | 5.78 | 869,435 | 3.2 |
Export Income
| Category | Description | This Year | This Year % | Last Year | Last Year % | 2 Years Ago | 2 Years Ago % |
|---|---|---|---|---|---|---|---|
| Total revenue | Total revenue | 37,818,188 | 100 | 37,250,093 | 100 | 27,136,995 | 100 |
| Domestic | Domestic | 3,079,487 | 8.14 | 4,012,677 | 10.77 | 2,522,547 | 9.3 |
| International | International | 34,738,701 | 91.86 | 33,237,416 | 89.23 | 24,614,448 | 90.7 |
| China | China | 11,864,358 | 34.15 | 10,246,657 | 30.83 | 4,980,324 | 20.23 |
| Singapore | Singapore | 11,080,560 | 31.9 | 10,899,652 | 32.79 | 9,207,648 | 37.41 |
| India | India | 2,780,431 | 8 | 2,654,555 | 7.99 | 2,302,423 | 9.35 |
| Vietnam | Vietnam | 2,100,977 | 6.05 | 2,169,808 | 6.53 | 1,594,335 | 6.48 |
| Hong Kong | Hong Kong | 587,095 | 1.69 | 673,552 | 2.03 | 476,193 | 1.93 |
| Other countries | Others | 6,325,280 | 18.21 | 6,593,192 | 19.84 | 6,053,525 | 24.59 |
Other Income
| Operating Other Income | Non-Operating Other Income | Share of Profit |
|---|---|---|
| 1710 · As of year: 894621.0 · Description: Total other income · As of yesteryear: 2154172.0 · As of year before yesteryear: 869435.0 · 1711 · As of year: 894621.0 · Description: Other income from operations · As of yesteryear: 2154172.0 · As of year before yesteryear: 869435.0 · 85934.0 · Description: Gain on sales of assets · As of yesteryear: 711342.0 · As of year before yesteryear: 170615.0 · 0.0 · Description: Reversal on impairment of vessels · As of yesteryear: 846834.0 · As of year before yesteryear: 0.0 · 606698.0 · Description: Interest income · As of yesteryear: 468114.0 · As of year before yesteryear: 541126.0 · 201989.0 · Description: Others · As of yesteryear: 127882.0 · As of year before yesteryear: 157694.0 | 1712 · As of year: 0.0 · Description: Other income not from operations · As of yesteryear: 0.0 · As of year before yesteryear: 0.0 | 1713 · As of year: 171313.0 · Description: Share of profit · As of yesteryear: 148197.0 · As of year before yesteryear: 93669.0 |
Product / Service Characteristics
Introduction
Regional Container Lines Public Company Limited and its companies in the group (“RCL” or the “Group”) operates on three core lines of business, namely;
Shipper-Owned-Container (SOC),
Carrier-Owned-Container (COC) and
Value-added logistic services.
Business Type
3115
Business Groups
| Business Group | Description | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Container Shipping | Business operations RCL is a Thai-based container shipping line incorporated in 1980 and listed on the Stock Exchange of Thailand since 1988. The Company operates on three main lines of business, namely; Shipper-Owned-Container (SOC), Carrier-Owned-Container (COC) and Value-added logistic services. The geographical business scope is the Asian continent with business activities covering North and South East Asia, Indian Sub-Continent, Middle East, Red Sea, East Africa and Mexico. The Group currently operates a fleet of 46 container vessels with sizes ranging from 388 TEUs to 11,714 TEUs. For its COC business, the Group also operates a container box fleet of 191,816 TEUs comprising of both owned and leased boxes. RCL also has a network of 127 offices comprising both owned-offices and agency representations to serve and support its customers and their business activities. Today, RCL is recognized as a leading COC and SOC operator by both peers and customers alike in the Intra Asia, Indian sub-continent, Middle East and East Africa. 2025 made milestone of expanding into new trade lane (Far East- Latin America) service which is the first direct service from RCL connecting China, Korea to Mexico. In the same year, RCL also participated in new service fortnightly from CN to SA (Jeddah) covering Sokhna and Aqaba. Lines of Business RCL also operates its own COC business with a fleet of 191,816 TEUs comprising of both owned and leased boxes to support its customer’s activities. These boxes are offered directly to exporters and importers to load for transportation in the trading lanes that RCL serves. RCL has concentrated its effort to grow its COC business scale and its customer relationships with both BCOs (Beneficial cargo owners) as well as the international and local freight forwarder customers. SOC or Shipper owned containers entails RCL providing space to container owning customers. Customers include main-line operators, non-vessel operating common carriers (NVOCC), ISO tank operators and other container box owners requiring transportation of their boxes between ports. Such “hub and spoke” activities are common to both MLO, NVOCC, ISO tank or other types of container operators today as they typically link up smaller ports with larger hubs for transshipment onto larger ships which travel in both the East West trades or North South in the case of Oceania. Privileges and restrictions of the Company to perform business are described below. The Company and Company’s subsidiaries receives the BOI investment promotion certification for 10 vessels as shown in the table.
Under the BOI promotion in Thailand, those 10 vessels are granted Tax privileges as follows:
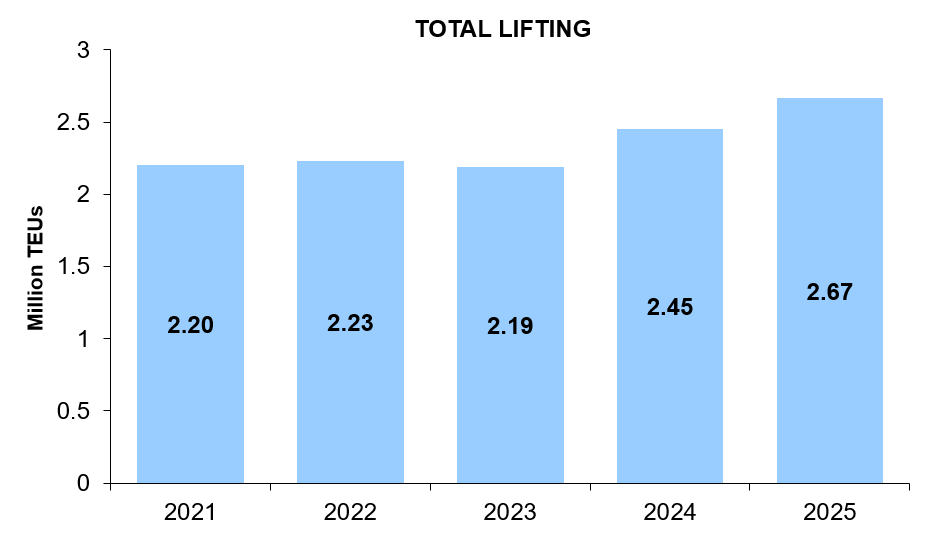
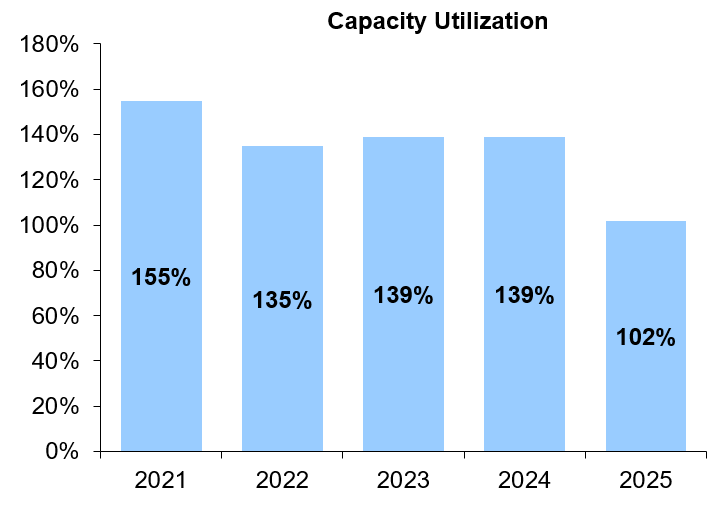
In addition, the Company also has another 4 vessels, namely Uru Bhum, Vira Bhum, Intra Bhum, and Siri Bhum which are applied and eligible for rights under Royal Decree No. 314 after the end of BOI promotion. Aside from the above mentioned, one of the Company’s subsidiaries in Singapore, namely Regional Container Lines Pte. Ltd., currently owning 25 vessels are entitled to exempt from corporate income tax for an indefinite period. Additionally, the Subsidiary is also exempted from import duties under ITA S13A for vessels imported into the country. Total Liftings 2025 RCL liftings surged significantly by 19.1% for COC, while SOC was -13.7%. RCL’s total liftings increased 8.8% with a utilization ratio of 102%.
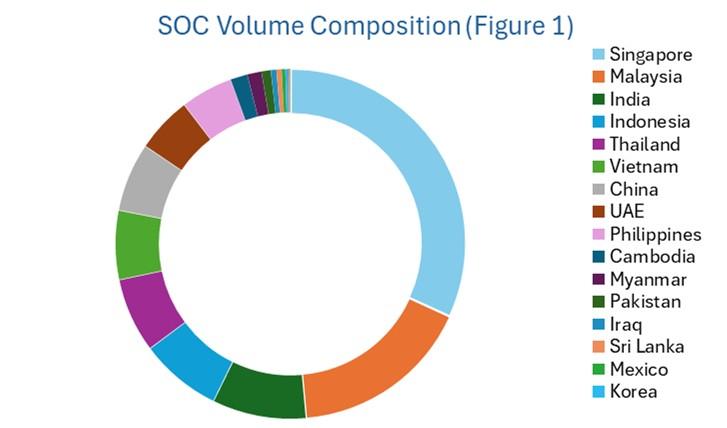
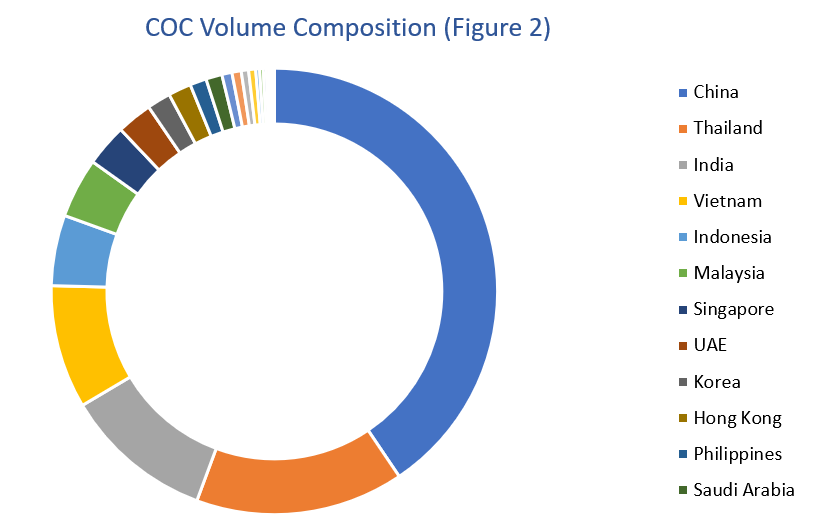
Trade Composition RCL’s SOC activities are largely focused in Singapore. PSA which operates the Singapore terminals is a global transshipment hub for many of the main line operators who are RCL’s customers. For COC in Figure 2, the top three export areas (PRC, Thailand and India) made up almost 66% of the volume composition. Total lifting
Figure 1 shows the SOC volume composition by origin ports of loading.
Figure 2 shows the COC volume composition by origin ports of loading.
| |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Logistics | The logistics industry in 2025 continued to face challenges, including freight rate volatility, intense competition, and global supply chain shifts. Despite these conditions, 2025 was a year of resilience, growth, and expansion for the RCL Logistics Group. We focused on deepening our network, investing in our people, and providing value-added services to our customers. In 2025, the RCL Logistics Group expanded its presence with additional offices in Hong Kong and Vietnam, increasing our network coverage to 11 offices across 5 countries in Asia. Our logistics volume grew by 10%, while revenue increased by 20% compared to 2024. This growth was driven by an expanded customer base, strengthened customer relationships, and the development of new business opportunities and stellar service offered to both existing and new customers. As a key group focus on delivering value-added services, RCL Logistics increased customs clearance personnel in Thailand to meet rising demand. We also deployed dedicated trucking fleets for specific customers in Thailand to streamline their supply chain movements. As a result, door-to-door deliveries and value-added service volumes increased significantly in 2025 compared to previous years. Indonesia, with its thousands of islands, presents complex logistics challenges for customers moving cargo across regions, particularly for newly established factories. Through our dedicated agent network in Indonesia, we successfully handled numerous inter-island shipments, helping to ease supply chain pain points for our customers. In addition, we managed port-to-door deliveries for DG Class 1 military shipments in Indonesia, which required specialized expertise, meticulous planning, strict compliance, and careful handling. China remained a strategically important market for RCL Logistics in 2025, as many of our new customers are China-based. Our joint-venture company in China strengthened its team with additional experienced personnel to meet increasing demand and ensure smooth operations for customers, not only at major seaports but also through offices along the Yangtze River region. India continued to be an important emerging market for RCL Logistics. Our joint-venture company focused on laying the foundation for network expansion across PAN-India in 2026. As part of our digital transformation journey, the RCL Logistics Group implemented new operational systems across the organization to enhance process standardization, data visibility, and operational control. These system enhancements supported better decision-making, strengthened internal coordination, and supported the Group’s growing scale and complexity. We also introduced automated reporting solutions to enhance process efficiency, data accuracy, and operational visibility across the organization. Looking ahead to 2026, RCL Logistics aims to further expand its regional network across Asia, strengthen end-to-end value-added services, enhance AI-driven digitalization and process efficiency, grow its customer base, and build long-term partnerships with customers. The Group remains committed to sustainable growth, operational excellence, and earning customer trust. |
Research & Development
Has R&D Policy (Y/N)
No
Introduction
Overview
In 2025, RCL continued to strengthen its Information Technology capabilities to support business growth, operational resilience, and digital transformation across regions. The focus remained on enhancing customer experience, improving internal productivity, modernizing core systems, and reinforcing infrastructure, cybersecurity, and compliance foundations to align with the Company’s expanding operational footprint and evolving business environment.
IT initiatives were implemented with an emphasis on stability, scalability, governance, and readiness for future growth, ensuring that digital services effectively support both operational and strategic objectives.
Major Developments in 2025
Digital Customer Experience and Service Enablement
In 2025, RCL continued to enhance its digital customer experience through ongoing improvements to online platforms and service channels. The new E-Service platform progressed through ongoing enhancement and preparation during the year, with core system architecture, user interface redesign, and internal process integration substantially completed. The platform is designed to support key customer activities such as booking, shipping instruction, container tracking, and service inquiries through a more intuitive and scalable digital interface, with a planned full launch in 2026.
To further improve customer interaction and service efficiency, a comprehensive chatbot was introduced to support booking inquiries, container status checks, and general service guidance. Cargo tracking activities were also aligned with industry standards to ensure consistency of shipment status information across digital channels.
Productivity Improvement and Process Automation
To address increasing operational complexity, IT initiatives in 2025 focused on automation and productivity enhancement. Several systems were improved to streamline quotation coordination, invoice processing, and performance monitoring across locations, helping to reduce manual workload and improve operational consistency.
Automation was further introduced within finance and operational processes to support faster processing cycles, improved accuracy, and more efficient use of resources. These initiatives enable staff to focus on higher-value activities while supporting overall operational efficiency.
Business Enablement and Regional Expansion Support
IT systems were enhanced to support evolving business requirements and regional expansion. System capabilities were extended to accommodate inland operations and new regions, including support for time-zone differences, localized cut-off times, and region-specific operational processes.
Key business systems, including bunker management, commission calculation, service forecasting, and vendor management, were enhanced with improved logic, forecasting, and reporting capabilities. These enhancements support better planning, cost management, and decision-making across the organization.
Legacy System Modernization
A major focus in 2025 was the modernization of legacy systems to improve system reliability, scalability, and long-term sustainability. Some core systems were rebuilt or upgraded using newer technologies, covering vessel operations, terminal and depot data, and reporting modules.
System security and usability were strengthened through improved access control mechanisms and more user-friendly dashboards, enhancing both system protection and user productivity. These efforts reduce dependency on legacy platforms and prepare the IT landscape for future digital initiatives.
Infrastructure and Platform Enhancements
Throughout 2025, RCL continued to strengthen its IT infrastructure to support increasing digital demand and ensure business continuity. Key initiatives included upgrades to application platforms, databases, operating systems, and web hosting environments to improve performance, stability, and scalability.
Infrastructure capacity was optimized through cloud resource management, cost-efficient storage strategies, and automated scaling aligned with usage patterns. A new Electronic Data Interchange (EDI) infrastructure landscape was commissioned to improve processing performance, security, and transaction handling efficiency.
Secure access to documents and systems was enhanced through the adoption of modern collaboration platforms, reducing reliance on less secure legacy file-sharing methods. Business continuity and disaster recovery readiness were further strengthened through high-availability and standby system configurations.
Compliance and Governance
In 2025, RCL continued to strengthen its Information Technology compliance and governance framework to support regulatory requirements, data protection obligations, and secure operations across multiple jurisdictions. IT compliance efforts focused on aligning policies, processes, and system controls with applicable laws, industry standards, and internal governance requirements.
Key activities included ongoing review and enhancement of IT policies, access controls, and system governance practices to support information security, data privacy, and operational continuity. Compliance considerations were integrated into system enhancements, infrastructure changes, and new technology initiatives to ensure regulatory and control requirements were addressed from the planning stage.
Cybersecurity and Risk Management
In 2025, the risk landscape increasingly reflected external threats and human-related risks rather than system weaknesses. Phishing attempts and external scanning of public-facing systems remained key risk areas, requiring continuous awareness and vigilance.
To address these risks, RCL focused on strengthening security awareness, enhancing access controls, improving protection of external-facing systems, and reinforcing monitoring and response processes to minimize potential impact on business operations.
Conclusion
Through continued investment in digital platforms, infrastructure, cybersecurity, and compliance, RCL’s Information Technology function in 2025 played a critical role in supporting operational resilience, regulatory confidence, and future growth. By modernizing systems, enhancing service capabilities, and strengthening governance, IT has established a solid foundation to support the Company’s strategic objectives and long-term sustainability.
Ship Management
GHG Emission Reduction
Achievements in 2025
a.) Even though the total deadweight (ton) in 2025 increased by 3.05% over 2024 due to fleet expansion, it was ascertained that the fleet's overall CO2 emissions has fallen by 16.82% (2025 vs. 2024: gramCo2e/Deadweight. Distance) as a result of the improvement and well-managed strategy to lower fuel oil consumption.
b.) The whole fleet's CII rating complies with the requirements of the IMO, with no E rating.
c.) Utilizing biofuel on the pilot ship Piya Bhum successfully.
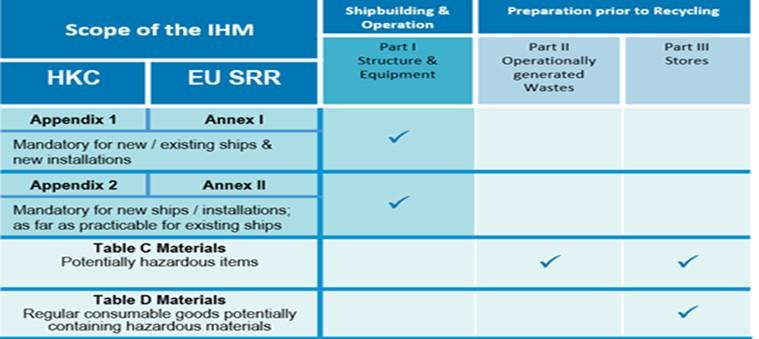
d.) All ships currently in service complies with the Hong Kong Convention's Inventory of Hazardous Materials (IHM). Part 1
Summary of Training Enhancement Plan 2025 Achievements
Plan Item | Implementation Details | Achievements |
1. Increase Training Frequency and Achieved 100% Officer Participation | Increased training frequency to cover all Officers in every position. | - Achieved 100% participation from all Officers as targeted. |
2. Monthly Training Programs for Ratings (Deck & Engine) | Conducted monthly training sessions for Ratings in both Deck and Engine departments. | - Enabled effective planning of crew assignment before joining vessels. |
3. Development of an E-Learning Platform | Developed an E-learning platform together with Video Delivery Outcomes (VDO) content aligned with job-specific courses. | - Platform and content are currently under development to match position-based training requirements. |
Target in 2026
a.) In order to achieve the IMO’s targeted CO2 intensity reduction by 2030, continuous improvements will be made to the CII Rating, in the following aspects :
Installation of Energy Saving Device with new design propeller.
Continue with hull cleaning during docking and apply with low friction paint.
Conduct propeller polishing annually after every dry docking to optimize propulsion efficiency and minimize fuel consumption.
Biofuel (B24), which can lower CO2 emissions by up to 20%, is one of alternative fuel that RCL can use swiftly and simply without modifying the engine.
IMO CO2 intensity reduction factor
Year | CO2 Reduction factor related to 2019 | Annual Increase Rate |
2023 | 5% | Implementation |
2024 | 7% | +2% |
2025 | 9% | +2% |
2026 | 11% | +2% |
2027 | 13.625% | +2.625% |
2028 | 16.250% | +2.625% |
2029 | 18.875% | +2.625% |
2030 | 21.500% | Target: 40% reduction vs 2008 |
b.) Advanced Management Capability Development and Improvement program for crew members, covering the following key areas :
Leadership and Management skills
Communication and Human factors
perational and Risk Management
Compliance and Management systems
Safety, Environmental and Energy Management
Training Methods;
In-house training, On board training, Scenario-based exercises and Case studies & group discussion
RSM Fleet Operation Management System (ROMs) to record and track crew training activities
c.) For container ship owners, ISO 14001:2015 is the global gold standard for an Environmental Management System (EMS). It provides a systematic framework to manage environmental responsibilities, specifically helping to mitigate the "E" in ESG.
By 2026, RCL Shipmanagement Pte. Ltd., a subsidiary of RCL Group, plans to meet this standard.
R&D Cost — Label
Research and development (R&D) expenses over the past 3 years (Million Baht)
Assets Used in the Business
Permanent Assets — Description
Vessels and Equipment
At the end of 2025, the Company and its subsidiaries own a total of 39 vessels and equipment with a net book value of 39,872 million Baht (the Company owns 12 vessels and its subsidiaries own 27 vessels). These vessels have capacities between 388 – 11,714 TEUs with DWT between 4,827 – 137,031 tons. They are used to carry general-purpose and reefer containers providing service transportation sailing within the regions and neighboring regions.
At the end of 2025, the Company and its subsidiaries have mortgaged 8 vessels to secure their loan credit facilities amounting to 12,473 million Baht.
At the end of 2025, the Company and its subsidiaries have engaged independent professional appraiser to perform vessel valuation.
Property and Premises
The Company and its subsidiaries own 3 office buildings for use as operating offices in Bangkok, Hong Kong and the People's Republic of China, with the net book value of the office building and building improvements totaling 327 million Baht.
Bangkok office is located at 127/35 Panjathani Tower, 30th Floor, Nonsi Road (Ratchadaphisek Road), Chong Nonsi Sub-District, Yannawa District, Bangkok 10120 with an area of 1,004 square meters and 127/21 Panjathani Tower, 16th Floor, Nonsi Road (Ratchadaphisek Road), Chong Nonsi Sub-District, Yannawa District, Bangkok 10120 with an area of 1,047 square meters, it is free from mortgage.
Hong Kong office is located at 9 Des Voeux West Street, 11th Floor with an area of 6,884 square feet and it is free from mortgage.
The office in the People's Republic of China is located at No. 18 Xi Zang Middle Road, 26th Floor, Harbor Ring Building, Huangpu District, Shanghai, with an area of 1,269 square meters and it is free from mortgage.
The condominium units in Singapore are located at 51B Lorong Sarhad, Sarhad Ville, with an area of 1,281 square feet, and 51C Lorong Sarhad, Sarhad Ville, with an area of 1,281 square feet, it is free from mortgage.
Permanent Assets — Appraisal
| Asset | Ownership | Obligation | Appraisal Value | Description |
|---|---|---|---|---|
| Vessels and Equipment | Company and Subsidiaries’ own | Mortgaged 8 vessels to secure their loan credit facilities | 39,872 | Unit: Million Baht |
| Property and Premises | Company and Subsidiaries’ own | Free from mortgage | 327 | Unit: Million Baht |
Intangible Assets — Description
Intangible assets consist of computer software, which is amortized on a straight-line basis over its useful life of 3 years.
Intangible Assets — Appraisal
| Asset | Type | Type (if Other) | Appraisal Value | Description |
|---|---|---|---|---|
| Intangible assets | Others | Program Computer | 0.17 | Unit: Million Baht |
Has Subsidiaries Investment Policy (Y/N)
Yes
Subsidiaries Investment Policy — Description
The Company has investments in subsidiaries as presented in “Shareholding Structure of the Group” The Company's investment policy is mainly to invest in businesses relating to the marine transportation business and value-added logistic services.
Marketing Policy & Competition
Reporting Mode
3117
Marketing Policy (Overall)
Marketing Nature
As the Group has subsidiaries in various countries in the region i.e. Thailand, Singapore, Hong Kong, Malaysia, the Philippines, the People's Republic of China and India, thus, the revenue structure of the Group can be categorized by geography and divided by the company & its subsidiaries. However, in fact, the Group manages its business in the form of a regional network (Regional Network). The container transportation service routing provided by the Group is among several countries, and sometimes the route could service up to 4 - 5 ports in a few countries. Therefore, it is difficult to categorize the income of each port according to their geographical income structure. This network management enables the Group to provide more thorough and efficient service coverage to meet our customers’ demand. At the same time, the Group’s large fleet size enables the Group to provide higher frequency and more regular service which is a strategic advantage over competitors.
In the case of Main Line Operators (MLO) or SOC customers, the Group uses direct distribution method whereas for direct shippers/consignees or COC customers, the Group uses Agents to distribute our services. In countries where there is high volume demand of inbound or outbound or both, the Group will establish a subsidiary/associated company to act as an Agent. But if the volume is minimum, the Group will appoint representatives in that country to provide the service and manage the sales through management fee. The Group can terminate the contract with the appointing representative if the representative’s performance is poor and/or had breached the contract. At present, the Group has few representatives. Most of them are subsidiaries or affiliates of the Group.
Regions – Development
a.) Geographical Offices
For 2025, there were new agents’ appointment in Berbera (Bebera), India (Gangavaram), Sudan (Port Sudan), Mexico (Manzanillo) and Hong Kong (Zhongshan, Zhuhai). With this, the total numbers of geographical offices increased to 127.
b.) ServiceDevelopment
In 2025, RCL successfully streamlined key services and expanded network coverage to align with evolving market trends. This was accomplished through economies of scale, strategic rationalization, and optimization in collaboration with consortium partners. The Company enhanced its service network in Intra-Asia trade while strengthening its presence in West Asia and the Middle East. RCL also participates in a new service in November connecting Indian Subcontinent to Middle East. Additionally, RCL extended its reach into East Asia, South Asia, and the Middle East with new addition of Mexico.
Future Plans
In 2026, the global economy is expected to grow steadily. The International Monetary Fund (IMF) forecasts global GDP growth at 3.3%, while the World Bank estimates 2.6%. Developing countries, especially in Asia, are growing faster than advanced economies. Southeast Asia, India, and the Middle East are becoming more important in global trade.
In the shipping industry, the number of container ships continues to grow. In 2026, ship capacity is expected to increase by 3.5–4%, while demand is growing at only 3%. This means there will be more ships than needed, which could lower freight rates and increase competition.
Geopolitical issues remain a challenge. The conflict in the Red Sea has disrupted shipping routes, and many ships are still avoiding the Suez Canal. At the same time, U.S. trade policies continue to affect global trade flows. However, the Panama Canal has recovered from past water shortages, and in early 2026, water levels are at record highs, allowing normal operations.
Southeast Asia, India, and the Middle East are benefiting from companies moving production out of China. India is expected to grow by 6.5% in 2026, supported by strong local demand and government programs. Investment in artificial intelligence (AI) and digital technology is also growing fast in Asia, especially in data centers and logistics.
Latin America is another region with potential. China is increasing exports to South America, and countries like Brazil, Mexico, and Chile are becoming more important in global trade. The World Bank expects Latin America to grow by 2.3% in 2026.
RCL will continue to grow by focusing on new opportunities and adapting to global changes. We will strengthen our presence in Southeast Asia, India, and the Middle East, and expand further into South America and West Asia. We will also focus on niche and less-developed trade routes, especially within Asia, which are less affected by global disruptions.
In 2026 and 2027, RCL will receive new ships to grow our fleet. These ships are more efficient and environmentally friendly, helping us reduce costs and improve service.
Our people remain at the heart of our success. With strong leadership and a focus on results, we will support our teams to overcome challenges and drive progress. By staying flexible, innovative, and customer-focused, RCL is ready to grow and succeed in the changing global market.
Industry & Competition (Overall)
Industry Competition
Competition among container shipping carriers intensified during the preceding year as fleet capacity growth outpaced global trade demand. While container trade volumes grew modestly, new vessel deliveries continued to expand industry capacity, leading to structural oversupply in several major trade lanes.
The industry remains highly concentrated, dominated by a small number of large global carriers such as Mediterranean Shipping Company (MSC), Maersk, CMA CGM, COSCO Shipping, and Hapag-Lloyd. Strategic alliances and operational partnerships continued to shape competitive dynamics. Gemini Cooperation between Maersk and Hapag-Lloyd launched in 2025 aims to improve network efficiency and service reliability through shared vessel deployment and coordinated operation. Environmental regulations and emissions policies also began to influence competitive positioning, with carriers investing in newer, more fuel-efficient vessels.
Industrial Environment
In 2025, the global trade landscape is undergoing structural adjustments driven by evolving geopolitical tensions and strategic shifts in manufacturing and trade policies. As freight rates softened, carriers increasingly competed through service quality, network reliability, digital logistics solutions, and environmental initiatives rather than price alone. At the same time, geopolitical disruptions (Iran, Ukraine war) cause supply chain uncertainties occasionally resulting in temporary rate spikes, contributing to unstable pricing conditions and heightened competition among carriers.
The Asia trade outlook remains a key driver of global economic activity. The implementation of the Regional Comprehensive Economic Partnership (RCEP) agreement is facilitating smoother cross-border trade and investment flows, particularly in ASEAN. Meanwhile, China will promote balanced trade growth this year, but supply chain diversification strategies such as the China+1 policy continue to benefit neighboring economies, driving increased regional collaboration. This shift is creating new demand for intra-Asia logistics, including faster, more flexible supply chain solutions.
India is emerging as a strategic trade hub, Advancing EU trade agreements and ongoing U.S. tariff negotiations are opening significant opportunities for high-tech, engineering, and manufacturing industries. India-EU Foreign Trade Agreement (FTA) will experience a significant increase of commodities textile leather exports, marine product and automotive and engineering component boosting export trade volume.
In the Middle East and East Africa, trade growth is supported by seeing shift of container shipping to Mombasa and Dar es Salaam due to continued infrastructure investments and greater connectivity to Asia and Europe. With all these, growth factors such as East Africa improving economic recovery and Middle East oil economy aid expansion of growth. These trends present a significant opportunity for RCL to expand its footprint by strengthening key shipping services and enhancing operational efficiency.
RCL is strategically positioned to capitalize on these developments, focusing on optimizing service offerings across high-growth trade corridors. By aligning with market demand and building stronger ties within ASEAN, India, the Middle East, and Africa, we aim to deliver sustainable growth and value to our stakeholders in the long term.
The China Containerized Freight Index (CCFI) averaged at 1,107 points in 2025, which was significantly lower than 1,542 in 2024. The Houthi attacks have caused significant disruption to the global container shipping routes, creating an unexpected shift in the industry that extended well into 2025. US Imports from China expected to face tariffs pressure which might shift toward alternative sourcing to Southeast Asia. Geopolitical disruption might also cause temporary spikes in rate.
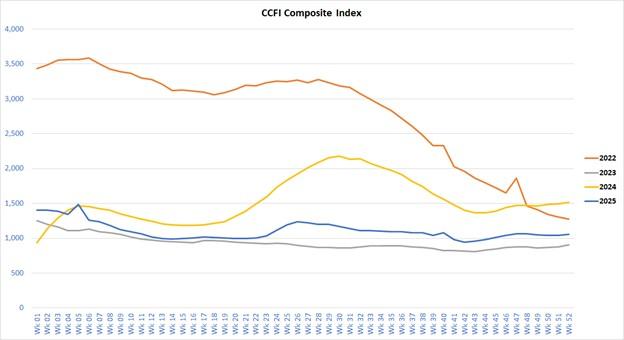
Source: Shanghai Shipping Exchange
In 2025, the container shipping market experienced decline as compared to 2024. Despite the decline, it was still stable as China’s export growth was driven by strong demand in key markets to East Asia. However, geopolitical tensions in the Red Sea region have led to disruptions in shipping routes. Houthi attacks have led to rerouting which resulted in longer transit times and increased operational costs. Nevertheless, the country still faces changes due to supply chain adjustments and geopolitical tensions, leading to a shift of supply chains to ASEAN countries and India. The rapid economic growth in Asia supported by favorable demographics and increased consumer and manufacturing spending, continued to bolster the region trade dominance in global trade. The imbalance between supply and demand is expected to significantly reduce freight rates. Volatility will remain high, driven by geopolitical tensions, shifting trade patterns (increased trade between China and other regions) and potential blank sailing schemes by carriers to manage capacity.
As of 31 December 2025, container fleet was 6,642 vessels, a slight increase from 6,398 in 2024. The growth was mainly from bigger vessels and subdue in TEU scrapped. While the total capacity increased from 31.0 million TEU at the end of 2024 to 33.3 million at the end of 2025. There was an increase in idling TEU from 126,539 in 2024 to 287,669 in 2025. Despite muted consumer demand, a surge in freight rates was observed in 2025, driven by the Red Sea crisis and subsequent rerouting of vessels. Carriers adjusted their operations by optimizing sailing routes, temporarily reducing their scheduled services, and redeploying vessels to meet shifting demand patterns.
The current outlook of world fleet capacity for cellular container vessels of different size range is presented as follows:
Fleet as at: | End 2025 | End 2026 | End 2027 | %TEU growth 2025-2026 | %TEU growth 2026-2027 | |||
Nominal TEU | No. | TEU | No. | TEU | No. | TEU | ||
>18,000 | 207 | 4,498,947 | 213 | 4,643,831 | 256 | 5,572,031 | 3.2% | 20.0% |
15,200-17,999 | 241 | 3,850,229 | 265 | 4,239,981 | 299 | 4,789,229 | 10.1% | 13.0% |
12,500-15,199 NPX* | 343 | 4,714,392 | 367 | 5,043,390 | 406 | 5,568,948 | 7.0% | 10.4% |
10,000-12,499 | 231 | 2,546,441 | 244 | 2,693,201 | 269 | 2,968,101 | 5.8% | 10.2% |
7,500-9,999 | 541 | 4,762,884 | 570 | 5,011,402 | 619 | 5,442,374 | 5.2% | 8.6% |
5,100-7,499 | 542 | 3,409,137 | 551 | 3,468,257 | 564 | 3,551,171 | 1.7% | 2.4% |
4,000-5,099 | 646 | 2,929,943 | 662 | 3,000,467 | 691 | 3,131,613 | 2.4% | 4.4% |
3,000-3,999 | 343 | 1,166,970 | 365 | 1,241,588 | 389 | 1,317,582 | 6.4% | 6.1% |
2,000-2,999 | 907 | 2,309,952 | 918 | 2,335,092 | 943 | 2,402,192 | 1.1% | 2.9% |
1,500-1,999 | 826 | 1,446,043 | 837 | 1,465,824 | 880 | 1,544,390 | 1.4% | 5.4% |
1,000-1,499 | 845 | 978,935 | 881 | 1,021,286 | 907 | 1,050,535 | 4.3% | 2.9% |
500-999 | 780 | 577,269 | 798 | 589,633 | 809 | 597,415 | 2.1% | 1.3% |
100-499 | 217 | 66,814 | 236 | 72,734 | 241 | 74,616 | 8.9% | 2.6% |
Total | 6,669 | 33,257,956 | 6,907 | 34,826,686 | 7,273 | 38,010,197 | 4.7% | 9.1% |
Adjusted Total | 6,669 | 33,257,956 | 6,787 | 34,486,686 | 7,063 | 37,360,197 | 3.7% | 8.3% |
Annual Growth | 7.20% | 3.7% | 8.3% | |||||
Source: Alphaliner, Monthly Monitoring January 2026
Market Outlook for Container Activity
Year 2026 would see a stable growth prospect as indicated in The International Monetary Fund (IMF) forecast at 3.1%. The growth is broad-based in Asia Pacific region and emerging economies. Much potential remains India, ASEAN, Middle East, Red Sea and East Africa with growth rate higher than global growth.
Global supply chain disruptions due to the Red Sea crisis and drought-driven cuts at the Suez Canal. Significant capacity adjustment on major trades with US West and Coast routes foresees freight rates to remain volatile. Carriers may implement more capacity management strategies such as blank sailings and schedule adjustments, to stabilize rates amid fluctuating cargo demand. Additionally, increased geopolitical tensions such as Iran conflict could further challenge global logistics, prompting businesses to diversify their supply chain networks and adopt more resilient strategies.
Projection
GDP Growth * | 2024 | 2025 | 2026 | 2027 |
World | 3.2 | 3.2 | 3.1 | 3.2 |
US | 2.8 | 2.2 | 2.1 | 2.1 |
Euro | 1.6 | 1.6 | 1.1 | 1.4 |
Emerging market | 3.2 | 3.2 | 4.0 | 4.2 |
China | 4.8 | 4.5 | 4.2 | 4.2 |
India | 7.0 | 6.5 | 6.2 | 6.4 |
Asean 5# | 4.5 | 4.5 | 4.1 | 4.3 |
Container Volume (Total Trade) | 5.4 | 2.8 | 2.5 | 5.0 |
Average of growth rates for export and import volumes (goods and services)
Source: World Economic Outlook 2026, IMF; Clarksons Container Intelligence Monthly December 2025
* Figures are in percentage
On the supply side, capacity growth is expected to grow in 2026 by 5.0% with 2.5 million TEUs of net capacity due. Majority of capacity growth in 2025 is expected to be absorbed by the East-West services continuing to Asia to Europe / US routes with the Alliances offering direct calls. Capacity in the Intra-Asia trade is expected to remain stable in 2026. Maersk paired with Hapag-Lloyd under Gemini, HMM.
Procurement of Products & Services
Reporting Mode
3117
Procurement (Overall)
Capacity, Network and Fleet Deployment
In 2025, RCL operated 46 container vessels. Of the 46 vessels operated, 39 vessels were owned whilst 7 were chartered in for various term periods.
The group in 2025 continued to cautiously balance the fleet deployment with a strategic mix of owned versus chartered ratio. The flexibility allowed RCL to achieve a competitive cost structure and meet incremental demand in selective trade lanes.
The average utilization factor for 2025 remained at 102%, consistent with the level in 2024.
RCL’s Fleet Composition (Nominal Capacity) | As of 2025 | As of 2024 | ||||
Number of Vessels | Capacity (TEUS) | % | Number of Vessels | Capacity (TEUS) | % | |
Owned | 29 | 94,005 | 60 | 29 | 85,975 | 56 |
Chartered in | 7 | 12,009 | 8 | 8 | 18,763 | 12 |
Chartered out | 10 | 47,738 | 31 | 9 | 46,780 | 31 |
Space Purchase | 1,809 | 1 | 1,009 | 1 | ||
Number of Vessels Operating | 46 | 155,561 | 100 | 46 | 152,527 | 100 |
RCL deploys its fleet across its four Regions as well as within each Region. The Group manages its flexibility through the use of added chartered vessels, slot purchases, reassignments of differing vessel sizes and realignment of services to meet the changing cargo trade patterns.
RCL Fleet Profile 2025
at fleet as 31st December 2025
No. | Name | Flag | Year Built | Shipyard | Deadweight | Designed Capacity | Age | Cargo Gear |
1 | AKA BHUM | Singapore | 2006 | Koyo Dockyard Co., Ltd. Mihara, Japan | 66,940 | 5,888 | 19 | - |
2 | API BHUM | Singapore | 2004 | Hanjin Heavey Industries Co., Ltd. | 67,677 | 4,992 | 21 | - |
3 | ARAYA BHUM | Singapore | 2006 | Koyo Dockyard Co., Ltd. Mihara, Japan | 66,940 | 5,888 | 19 | - |
4 | ATI BHUM | Thai | 2018 | Zhejiang Hexin Shipyard, China | 4,985 | 388 | 7 | - |
5 | BHUDTHI BHUM | Singapore | 2007 | Koyo Dockyard Co., Ltd. Mihara, Japan | 72,807 | 6,310 | 18 | - |
6 | DANU BHUM | Singapore | 1996 | Singapore Shipbuilding & Engineering | 13,825 | 993 | 29 | 2x40 |
7 | GANTA BHUM | Singapore | 2005 | Hyundai Mipo Dockyard Co., Ltd. (H.M.D.) | 39,396 | 2,824 | 20 | - |
8 | HEMMA BHUM | Singapore | 2024 | Shanghai Waigaoqiao Shipbuilding, China | 86,800 | 7,092 | 1 | - |
9 | HIRANYA BHUM | Thai | 2007 | Hyundai Mipo Dockyard Co., Ltd. (H.M.D.) | 39,360 | 2,824 | 18 | - |
10 | HUNSA BHUM | Singapore | 2002 | Nordseewerke, Emden, Germany | 33,940 | 2,460 | 23 | 3x40 |
11 | INTRA BHUM | Thai | 2013 | Daesun Shipbuilding & Engineering Co., Ltd. | 13,021 | 958 | 12 | - |
12 | ISARA BHUM | Singapore | 2008 | Murakami Hide Shipbuilding Co., Ltd., Japan | 12,475 | 1,088 | 17 | - |
13 | JARU BHUM | Thai | 2018 | Jiangsu New Yangzi Shipbuilding Co., Ltd., China | 19,949 | 1,668 | 7 | - |
14 | JIRA BHUM | Singapore | 2024 | Shanghai Waigaoqiao Shipbuilding, China | 86,800 | 7,092 | 1 | - |
15 | KHUNA BHUM | Thai | 2018 | Jiangsu New Yangzi Shipbuilding Co., Ltd., China | 19,981 | 1,668 | 7 | - |
16 | KITI BHUM | Singapore | 1997 | Miho Shipyard Co., Ltd., Japan | 11,136 | 865 | 28 | 2x40 |
17 | KOTA TEMA | Singapore | 2024 | Shanghai Waigaoqiao Shipbuilding, China | 86,800 | 7,092 | 1 | - |
18 | KOTA SYDNEY | Singapore | 2024 | Shanghai Waigaoqiao Shipbuilding, China | 86,800 | 7,092 | 1 | - |
19 | LALIT BHUM | Thai | 2019 | Jiangsu New Yangzi Shipbuilding Co., Ltd., China | 19,779 | 1,668 | 6 | - |
20 | LILA BHUM | Singapore | 1997 | Miho Shipyard Co., Ltd., Japan | 11,482 | 865 | 28 | 2x40 |
21 | MAKHA BHUM | Thai | 2019 | Jiangsu New Yangzi Shipbuilding Co., Ltd., China | 19,823 | 1,668 | 6 | - |
22 | MITRA BHUM | Singapore | 2007 | Jiangsu Eastern Shipyard, China | 13,760 | 1,108 | 18 | - |
23 | NATTHA BHUM | Thai | 2023 | Cssc Huangpu Wenchong Shipbuilding Co., Ltd. | 24,712 | 1,930 | 2 | - |
24 | NAWATA BHUM | Singapore | 2008 | Jiangsu Eastern Shipyard, China | 13,853 | 1,108 | 17 | - |
25 | ORA BHUM | Singapore | 1997 | Kyokuyo Shipyard Coporation, Japan | 8,006 | 622 | 28 | 2x36 |
26 | OTANA BHUM | Singapore | 2008 | Jiangsu Eastern Shipyard | 13,727 | 1,022 | 17 | - |
27 | PANJA BHUM | Singapore | 2008 | Jiangsu Eastern Shipyard | 13,760 | 1,022 | 17 | - |
28 | PIRA BHUM | Singapore | 1997 | Kyokuyo Shipyard Coporation, Japan | 8,287 | 628 | 28 | 2x36 |
29 | PIYA BHUM | Singapore | 2016 | Guangzhou Wenchong Shipyard, China | 21,785 | 1,707 | 9 | - |
30 | RACHA BHUM | Singapore | 2008 | Stocznia Gdynia, Gdynia, Poland | 38,968 | 2,732 | 17 | - |
31 | SATTHA BHUM | Singapore | 2009 | Stocznia Gdynia, Gdynia, Poland | 38,968 | 2,732 | 16 | - |
32 | SIRI BHUM | Thai | 2013 | Daesun Shipbuilding & Engineering Co., Ltd. | 13,017 | 958 | 12 | - |
33 | URU BHUM | Thai | 2005 | Mitsubishi Heavy Industries Ltd - Nagasaki, Japan | 33,011 | 2,598 | 20 | - |
34 | USSAMA BHUM | Singapore | 2024 | Imabari Shipbuilding Co., Ltd.- Hiroshima Shipyard, Japan | 136,910 | 11,714 | 1 | - |
35 | VIRA BHUM | Thai | 2005 | Mitsubishi Heavy Industries Ltd - Nagasaki, Japan | 33,011 | 2,598 | 20 | - |
36 | VARANYA BHUM | Singapore | 2024 | IMABARI SHIPBUILDING CO., LTD.- HIROSHIMA SHIPYARD, JAPAN | 137,022 | 11,714 | 1 | - |
37 | WHUTTHI BHUM | Singapore | 2005 | Akerostsee, Wismar/Warnemuende Germany | 37,882 | 2,741 | 20 | - |
38 | ZIM BANGKOK | Thai | 2023 | Imabari Shipbuilding Co., Ltd.- Hiroshima Shipyard, Japan | 137,022 | 11,714 | 2 | - |
39 | ZIM THAILAND | Thai | 2022 | Imabari Shipbuilding Co., Ltd.- Hiroshima Shipyard, Japan | 137,022 | 11,714 | 3 | - |
TOTAL OWN CAPACITY 141,745 TEUs | ||||||||
Total 39 vessels with the average age of 14 years | ||||||||
SHIPS OPERATED ON CHARTERED
No. | Name | Flag | Year Built | Shipyard | Deadweight | Capacity | Age | Cargo Gear |
1 | CHANA BHUM | Singapore | 1996 | Singapore Shipbuilding & Engineering | 13,825 | 993 | 29 | 2x40 |
2 | GREEN EARTH | Singapore | 2019 | HYUNDAI MIPO DOCKYARD | 22,330 | 1,800 | 6 | - |
3 | GSL MAMITSA | Liberia | 2007 | HYUNDAI MIPO Dockyard Co | 39,277 | 2,824 | 18 | - |
4 | LITTLE WARRIOR | Liberia | 2015 | Jiangsu New Yangzi Shipbuilding Co., Ltd. | 24,470 | 1,781 | 10 | - |
5 | MTT SAISUNEE | Malaysia | 2019 | Fujian Mawei Shipbuilding Ltd., China | 15,381 | 1,162 | 6 | - |
6 | PALAWAN | Antigua and Barbuda | 2023 | Wenchong Shipbuilding | 24,744 | 1,930 | 2 | - |
7 | TB JINJIANG | Liberia | 1997 | SHIN KURUSHIMA DOCKYARD CO., LTD | 24,166 | 1,510 | 28 | - |
TOTAL CHARTERED CAPACITY 12,000 TEUs | ||||||||
Total 7 vessels with the average age of 14 years | ||||||||
RCL FLEET CAPACITY 153,745 TEUs
| No. Vessels | Capacity TEUs | % |
Owned | 39 | 141,745 | 92% |
Chartered | 7 | 12,000 | 8% |
No. of Vessels Operating | 46 | 153,745 | 100% |
Regional Offices and Agents 2025
Country | City | Company | Telephone | Fax |
BAHRAIN | Al Adiiyah Capital Govemorate | Alsharif Group W.L.L | (00973) 1751 5050 | (00973) 1751 5051 |
BANGLADESH | Chattogram | Integrated Transportation Services Limited (ITSL) | (880) 2333-313826 | (880) 31 710 847 |
BRUNEI | Muara | Ben Line Agencies (B) Sdn. Bhd. | (673) 222 0607 | (673) 222 0608 |
CAMBODIA | Phnom Phen Sihanoukville | Arrow Shipping Agency Co., Ltd. | (855-23) 880 241/ 242 | (855-23) 885 706/ 607 |
CHINA | Qingdao | Regional Container Lines Shipping Co., Ltd. | (86532) 8668 5577 | (86532) 86681966 |
Tianjin | Regional Container Lines Shipping Co., Ltd. | (86-22) 83191938 | - | |
Fangcheng | China Ocean Shipping Agency Fangcheng | (86532) 86681966 | (86770) 610 2204 | |
Guangzhou | Regional Container Lines Shipping Co., Ltd. | (8620) 83633326 | - | |
Shenzhen | Regional Container Lines Shipping Co., Ltd. | (86755) 2518 1150 | - | |
Xiamen | Regional Container Lines Shipping Co., Ltd. | (86592) 262 8359 | - | |
Ningbo | Regional Container Lines Shipping Co., Ltd. | (86574) 2787 2823 | - | |
Shanghai | Regional Container Lines Shipping Co., Ltd. | (86-21) 6132 4500 | - | |
Nanjing | Shanghai CIMC Grand International Logistics Co., Ltd. | (86-25) 83260500 | (8625) 83260568 | |
Dalian | China Marine Shipping Agency Liaoning Co., Ltd. | (86-411) 8255 1167 | (86-411) 82803858 | |
DJIBOUTI | Djibouti | Djibouti Shipping Services SARL | (253) 21354640 | (253) 21354660 |
EGYPT | Sokhna | Marine & Engineering Services Company | (002) 033991000 | - |
HONG KONG | Hong Kong | Regional Container Lines (H.K.) Limited | (852) 2526 3318 | (852) 2537 5463 / 5452 / 5456 |
INDIA | Chennai | RCL Agencies East India Pvt. Ltd. | (91 44) 4019 1600 | - |
New Delhi | RCL Agencies (India) Pvt. Ltd. | (91 11) 4951 2330 | - | |
Tughlakbad | RCL Agencies (India) Pvt. Ltd. | (91 11) 4951 2331/ | - | |
Dadri | RCL Agencies (India) Pvt. Ltd. | (91 11) 4951 2331/ | - | |
Sonipat | RCL Agencies (India) Pvt. Ltd. | (91 11) 4951 2331/ | - | |
Garhi Harsaru | RCL Agencies (India) Pvt. Ltd. | (91 11) 4951 2331/ | - | |
Jhattipur | RCL Agencies (India) Pvt. Ltd. | (91 11) 4951 2331/ | - | |
Moradabad | RCL Agencies (India) Pvt. Ltd. | (91 11) 4951 2331/ | - | |
Gandhidham | RCL Agencies (India) Pvt. Ltd. | (91 28) 36 299553 | - | |
Bangalore | Chakiat Shipping Services Pvt. Ltd. | (91 80) 2558 2096 | (91 80) 2558 9737 | |
Hyderabad | Chakiat Shipping Services Pvt. Ltd. | (91 40) 4904 5678 | (91 40) 4904 5688 | |
Haldia | Chakiat Shipping Services Pvt. Ltd. | (9133) 6615 2900 | (9133) 2289 2172 | |
Paradip | Chakiat Shipping Services Pvt. Ltd. | (9106722) 221101 | - | |
Tuticorin | Chakiat Shipping Services Pvt. Ltd. | (91 461) 425 2680 | (91 461) 4252681 | |
Cochin | Chakiat Shipping Services Pvt. Ltd. | (91 484) 266 6166 | (91 484) 266 8085 | |
Kolkata | Chakiat Shipping Services Pvt. Ltd. | (91 33) 6615 2900 | (91 33) 2289 2172 | |
Visakhapatnam | Chakiat Shipping Services Pvt. Ltd. | (91 891) 454 6444 | (91 891) 454 6455 | |
Vizag | Chakiat Shipping Services Pvt Ltd. | (91 891) 454 6444 | (91 891) 454 6455 | |
Krishnapatnam | Chakiat Shipping Services Pvt. Ltd. | (91 861) 237 7043 | - | |
Mumbai | RCL Agencies (India) Pvt. Ltd. | (91 22) 4942 6000 | - | |
Nava Sheva | RCL Agencies (India) Pvt. Ltd. | (9122) 274 70401 274 70397/98 | - | |
Pan India | Sea Trade Shipping (India) Pvt. Ltd. | (91 22) 66775000 | - | |
Ludhiana | Sea Trade Shipping (India) Pvt. Ltd. | (91161) 4500523 | - | |
Ahmedabad | Sea Trade Shipping (India) Pvt. Ltd. | (91 79) 66226622 | - | |
Jaipur | Sea Trade Shipping (India) Pvt. Ltd. | (91 141) 2221 061 (91 11) 46109000/35 | - | |
Baroda (Vadodara) | Sea Trade Shipping (India) Pvt. Ltd. | (91 265) 6626 116 /6161 | - | |
Hazira | Sea Trade Shipping (India) Pvt. Ltd. | (91 261) 234 0030 | - | |
Pipavav | Sea Trade Shipping (India) Pvt. Ltd. | (91 2794) 286 327 | - | |
Rajkot (Commercial Office for Pipavav) | Sea Trade Shipping (India) Pvt. Ltd. | (91 281) 257 603/ 257 6604 | - | |
Morbi | Sea Trade Shipping (India) Pvt. Ltd. | (91 2822) 296568 | - | |
Nashik | Sea Trade Shipping (India) Pvt. Ltd. | (91 253) 6601423 | - | |
Indore | Sea Trade Shipping (India) Pvt. Ltd. | (91 731) 4217600 | - | |
Pune | Sea Trade Shipping (India) Pvt. Ltd. | (91 20) 66061501 | - | |
Aurangabad | Sea Trade Shipping (India) Pvt. Ltd. | (91 731) 4217600 | - | |
Agra | Sea Trade Shipping (India) Pvt. Ltd. | (91 562) 2601040 | - | |
Moradabad | Sea Trade Shipping (India) Pvt. Ltd. | (91 591) 2430777 | - | |
Jalandhar | Sea Trade Shipping (India) Pvt. Ltd. | (91 76) 96002034/ (91 11) 46109035 | - | |
Kanpur | Sea Trade Shipping (India) Pvt. Ltd. | (91 512) 2331613 | - | |
Jodphur | Sea Trade Shipping (India) Pvt. Ltd. | (91 0291) 2980271/72 | - | |
Chandigarh | Sea Trade Shipping (India) Pvt. Ltd. | (91 172) 4616177 | - | |
Mundra (Operation office only) | Sea Trade Shipping (India) Pvt. Ltd. | (91 28) 38259146/114 | - | |
INDONESIA | Jakarta | PT Jasa Centina Sentosa | (6221) 3516602 | - |
Medan / Belawan | PT Bintika Bangunusa | (6261) 845 5883 | (6261) 8462909 8445808 | |
Surabaya | PT Jasa Centina Sentosa | (6231) 535 2609 | - | |
Palembang | PT Bintika Bangunusa | (62-711) 716 380 716 381 716 382 | (62-711) 716379 | |
Pontianak | PT Lintas Kumala Abadi | (62-561) 761070 / 736226 | (62-561) 764714 | |
Semarang | PT Blessindo Berjaya Logistic | (6224) 76430702 | - | |
Kota Makassar | PT Zona Baru Indoneisa | (62 411) 3632060 | - | |
Kota Banjarmasin | PT Blessindo Berjaya Logistic | (62 511) 6775916 | - | |
IRAQ | Al Basrah | Sharaf Shipping Company Iraq | (964) 7809293055 7703200070 | - |
JAPAN | Imari | Nagai Co., Ltd | (81) 955 271300 | (81) 955 27 1930 |
Shibushi | Yamashita Kaisouten Co., Ltd. | (81) 99 4721401 | (81) 99 473 2694 | |
Oita | Tsurusaki Sealand Transportation Co., Ltd. | (81) 97 5297230 | (81) 97 592 8550 | |
Hososhima | Hakko Unyu Co., Ltd. | (81) 982 560052 | (81) 982 56 0310 | |
Fukuyama | Kambara Logistics Co., Ltd. | (84) 981 3636 | (84) 981 3667 | |
Mizushima | Nippon Express Co., Ltd Mizushima Branch | (86) 523 0204 | (86) 523 1755 | |
Hiroshima | Mazda Logistics Co., Ltd | (82) 251 3232 | (82) 251 3076 | |
Niigata | Rinko Corporation | (81) 25 245 4113 | (81) 25 248 4113 | |
Kanazawa | Kanazawa Koun Corporation | (81) 76 268 1813 | (81) 76 268 1816 | |
Toyama | Fushiki Kairiku Unso Co., Ltd. | (81) 766 45 1139 | (81) 766 45 1186 | |
Otaru | North Star Transport Co., Ltd. | 0134 22 5101 | 0134 25 3831 | |
Tokyo | Mitsui-Soko Co., Ltd. | (81) 3 5962 4371 | (81) 3 5962 4401 | |
Yokohama | Mitsui-Soko Co., Ltd. | (81) 45 502 9311 | - | |
Osaka | Mitsui Warehouse Terminal Service Co., Ltd. | (81) 66613 3201 | (81) 6 6613 6681 | |
Kobe | Mitsui-Soko Co., Ltd | (81) 78 845 9883 | - | |
Moji | Mitsui-Soko Kyushu Co., Ltd. | (81) 93 332 5328 | (81) 93 321 3873 | |
JORDAN | Aqaba | Euro Shipping Services Co. W.L.L. | 962 (6) 5160078 | - |
KENYA | Mombasa | Sharaf Shipping Agency (K) Ltd. | (5441) 2222966 | (25442) 222 1915 |
KUWAIT | Salmiya | Al Kazemi International General Trading & Contracting Group Co., WLL. | (965) 22022225 Ext. 236 | (965) 25723161 |
MALAYSIA | Johore Bahru / Pasir Gudang | RCL Agencies (M) Sdn. Bhd. | (607) 352 2388 | (607) 352 1288 |
Bintulu | Bendara Shipping Agencies Sdn. Bhd. | (6086) 299 390 | - | |
Kota Kinabalu | Bendara Shipping Agencies Sdn. Bhd. | (6088) 335 791 | - | |
Penang | RCL Agencies (M) Sdn. Bhd. | (604) 228 8127 | - | |
Port Klang | RCL Agencies (M) Sdn. Bhd. | (603) 3342 2722 | (603) 3342 2871 | |
MALDIVES | Male | One World Logistics Maldives Pvt. Ltd. | (960) 330 0610 | (960) 301 1999 |
MEXICO | Mexico | AGENCIA NAVIERA TAILANDIA SA DE CV/MARITIMEX GROUP | (52) 5550892222 | - |
MYANMAR | Yangon | RCL (Myanmar) Co., Ltd. | (95) 1202 065/ 067/ 103 | - |
OMAN | Sohar | Global Corp Logistics LLC. | (968) 26755842 | (968) 26755891 |
Muscat | Global Corp Logistics LLC. | (968) 2470 2744 | (968) 2470 1748 | |
PAKISTAN | Karachi | United Marine Agencies (Pvt.) Ltd. | (9221) 111111862 | (9221) 3514 7951 |
PHILIPPINES | Cebu | Eagle Express Lines, Inc. | (6332) 420 2365 268 7994 | - |
Davao | Eagle Express Lines, Inc. | (6382) 321 7139 | - | |
General Santos | Eagle Express Lines, Inc. | (6391) 321 7139 | - | |
Cagayan | Eagle Express Lines, Inc. | (632) 4202365 | - | |
Zamboanga | Eagle Express Lines, Inc. | (632) 4202365 | - | |
Iloilo | MStar Ship Agencies | (632) 8564 8888 | - | |
Manila | RCL Feeders Phils., Inc. | (632) 8815 3187 | - | |
QATAR | Doha | GWC Shipping Services | (974) 4449 3000 | (974) 4449 3100 |
SAUDI ARABIA | Dammam | Global Corp Logistics LLC | (966) 1382 10760 | - |
Jeddah | Pride Shipping Company Ltd. | (966)126521058 | (966) 1265 28258 | |
SINGAPORE | Singapore | RCL Feeder Pte. Ltd. | (65) 6220 0388 | (65) 6221 9760 |
SOUTH KOREA | Pusan | KUKBO AGENCY CO., LTD. | (82)-51-461-0984 | (82)-51-461-0987 |
Seoul | KUKBO AGENCY CO., LTD. | (82)-2-2151-9660 | (82)-2-771-2502 | |
SRI LANKA | Colombo | Delmege Forsyth & Co. (Shipping) Ltd. | (9411) 772 9557 772 9570 | (9411) 772 9556(662) 296 1096 |
TAIWAN | Taipei | Bravi International Co., Ltd | (88)62 89795939 | (88)62 25701118 |
Taichung | Bravi International Co., Ltd | (88)62 89795939 | (88)64 23218057 | |
TANZANIA | Tanzania | African Shipping Limited | (255-22) 218 3737 | - |
THAILAND | Bangkok | Regional Container Lines Public Company Limited | (662) 296 1096 | (662) 296 1098 |
Bangkok (Agent) | Ngow Hock Co., Ltd. | (662) 295 3737 | (662) 296 1525 | |
Laem Chabang | Ngow Hock Agency Co., Ltd. | (6638) 330 727-9 | (6638) 330 730 | |
Songkhla | Songkhla Shipping Agency Co., Ltd. | (6674) 245 574 | (6674) 232 345 | |
UINTED ARAB EMIRATES | Dubai | RCL Shipping L.L.C. | (00 9714) 4946400 | - |
VIETNAM | Ho Chi Minh | RCL (Vietnam) Co., Ltd. | (8428) 3818 1522 | - |
Haiphong | RCL (Vietnam) Co., Ltd. - Haiphong Branch | (84225) 3668155 | - | |
Hanoi | RCL (Vietnam) Co., Ltd. - Hanoi Representative Office | (8424) 32000288 | - |
RCL’s sailing routes link the countries in North Asia, South East Asia, Indian Sub-Continent, Middle East, Red Sea, East Africa and Mexico with each other through its main trunk services.
In addition, secondary services within regions and between regions are also available to complement the main trunk services. In total RCL operates 46 services independently and collaboratively through joint services and slot exchanges and slot ownerships. The details of vessels’ trading route have been established on RCL’s website at https://www.rclgroup.com/Default.aspx.
Vessels’ Trading Route as at December 31st, 2025
No. | Type of Vessel | Operator | Vessel Name | Vessel Code | Trading Routes | Service | Changes to Trading Routes | When Changed | Days per Round Voyage |
1 | Rcl Own Vsl. | RCL | AKA BHUM | AKB | Jebel Ali(T4)-Jebel Ali(T2)-Cochin-Colombo-Chennai-Colombo-Cochin-Jebel Ali(T4) | RIG3 | NA | NA | 28 |
2 | Rcl Own Vsl. | RCL | ATI BHUM | ATB | Singapore-Pasir Gudang-Singapore-Palembang-Singapore | RPE2 | NA | NA | 7 |
3 | Rcl Own Vsl. | RCL | BHUDTHI BHUM | BTB | Vietnam(CMT)-Laemchabang-Portklang(Wp)-Nhava Sheva-Jebel Ali-Dammam-Mundra-Portklang(Wp)-Vietnam(CMT) | RGA4 | NA | NA | 42 |
4 | Rcl Own Vsl. | RCL | DANU BHUM | DNB | Vietnam(C8Q)-Portklang(Wp)-Kolkata-Kattupalli-Vietnam(C8Q) | RCH9 | NA | NA | 28 |
5 | Rcl Own Vsl. | RCL | GANTA BHUM | GTB | Shanghai-Qingdao-Pusan-Mexico-Shanghai | RFL | NA | NA | 49 |
6 | Rcl Own Vsl. | RCL | HEMMA BHUM | HMB | Shanghai-Ningbo-Shekou-Singapore-Portklang(Wp)-Nhava Sheva-Mundra-Karachi-Portklang(Wp)-Singapore-Shanghai | RWA2 | NA | NA | 42 |
7 | Rcl Own Vsl. | RCL | HIRANYA BHUM | HRB | Mundra-Nhava Sheva-Jebel Ali(T3)-Jebel Ali-UMM QASR-Jebel Ali(T3)-Jebel Ali-Mundra | RWG | NA | NA | 21 |
8 | Rcl Own Vsl. | RCL | HUNSA BHUM | HSB | Hongkong-Shekou-Nansha-Surabaya-Semarang-Jakarta-Portklang(Wp)-Portklang(Np)-Hongkong | RCI02 | NA | NA | 21 |
9 | Rcl Own Vsl. | RCL | JARU BHUM | JRB | Shekou-Nansha-Laemchabang-Bangkok(PAT)-Laemchabang-Shekou | RBS8 | NA | NA | 14 |
10 | Rcl Own Vsl. | RCL | JIRA BHUM | JIB | Shanghai-Ningbo-Shekou-Singapore-Portklang(Wp)-Nhava Sheva-Mundra-Karachi-Portklang(Wp)-Singapore-Shanghai | RWA2 | NA | NA | 42 |
11 | Rcl Own Vsl. | RCL | KHUNA BHUM | KNB | Bangkok(PAT)-Bangkok(SSW)-Laemchabang-Vietnam(CLI)-Ningbo-Shanghai-Laemchabang-Bangkok(PAT) | RBC13 | NA | NA | 21 |
12 | Rcl Own Vsl. | RCL | KITI BHUM | KTB | Singapore-Zamboanga-Cebu-Cagayan de oro-Singapore | RSP6 | NA | NA | 14 |
13 | Rcl Own Vsl. | RCL | LALIT BHUM | LTB | Bangkok(SSW)-Laemchabang-Haiphong-Shekou-Nansha-Laemchabang-Bangkok(SSW) | RBH9 | NA | NA | 14 |
14 | Rcl Own Vsl. | RCL | LILA BHUM | LLB | Singapore-Songkhla-Singapore | RSE | NA | NA | 7 |
15 | Rcl Own Vsl. | RCL | MAKHA BHUM | MKB | Bangkok(SSW)-Laemchabang-Haiphong-Shekou-Nansha-Laemchabang-Bangkok(SSW) | RBH9 | NA | NA | 14 |
16 | Rcl Own Vsl. | RCL | NATTHA BHUM | NHB | Laemchabang-Singapore-Jakarta-Singapore-Laemchabang | RTI02 | NA | NA | 21 |
17 | Rcl Own Vsl. | RCL | NAWATA BHUM | NWB | Singapore-Sihanoukville-Singapore | RCX2 | YES | P/O 11/12 | 7 |
Rcl Own Vsl. | RCL | NAWATA BHUM | NWB | Singapore-Shekou | ROP | YES | P/I 11/12 | ||
18 | Rcl Own Vsl. | RCL | ORA BHUM | ORB | Singapore-Zamboanga-Cebu-Cagayan de oro-Singapore | RSP6 | NA | NA | 14 |
19 | Rcl Own Vsl. | RCL | OTANA BHUM | OTB | Singapore-Sihanoukville-Singapore | RCX2 | NA | NA | 21 |
20 | Rcl Own Vsl. | RCL | PIRA BHUM | PRB | Shanghai-Nansha-Vietnam(C8Q)-Shanghai | RCV | NA | NA | 14 |
21 | Rcl Own Vsl. | RCL | PIYA BHUM | PYB | Nansha-Shekou-Hongkong-Sihanoukville-Laemchabang-Vietnam(THP)-Batangas-Manila-Nansha | RSK2 | NA | NA | 21 |
22 | Rcl Own Vsl. | RCL | RACHA BHUM | RCB | Vietnam(CLI)-Laemchabang-Singapore-Portklang(Np)-Chennai-Visakhapatnam-Portklang(Np)-Singapore-Vietnam(CLI) | RMV | NA | NA | 28 |
23 | Rcl Own Vsl. | RCL | SATTHA BHUM | STB | Qingdao-Shanghai-Ningbo-Nansha-Portklang(Wp)-Dar Es Salaam-Mombasa-Portklang(Wp)-Qingdao | REA | NA | NA | 56 |
24 | Rcl Own Vsl. | RCL | URU BHUM | URB | Dalian-Tianjin Xingang-Qingdao-Hongkong-Shekou-Vietnam(CLI)-Hongkong-Shekou-Incheon-Dalian | RNV | NA | NA | 21 |
25 | Rcl Own Vsl. | RCL | USSAMA BHUM | UMB | Qingdao-Shanghai-Ningbo-Nansha-Shekou-Singapore-Jebel Ali-Dammam-Singapore-Qingdao | RCG | NA | NA | 49 |
26 | Rcl Own Vsl. | RCL | VARANYA BHUM | VYB | Qingdao-Shanghai-Ningbo-Nansha-Shekou-Singapore-Jebel Ali-Dammam-Singapore-Qingdao | RCG | NA | NA | 49 |
27 | Rcl Own Vsl. | RCL | VIRA BHUM | VRB | Laemchabang-Vietnam(CMT)-Manila-Pusan-Qingdao-Shanghai-Laemchabang | RLM2 | NA | NA | 28 |
28 | Rcl Own Vsl. | RCL | WHUTTHI BHUM | WTB | Shanghai-Ningbo-Nansha-Singapore-Chennai-Gangavaram-Portklang(Wp)-Singapore-Shanghai | RFM2 | NA | NA | 35 |
29 | Charter In | RCL | CHANA BHUM | CNB | Singapore-Yangon(MIT)-Yangon(AWP)-Portklang(Wp)-Yangon(AWP)-Singapore | RSY | NA | NA | 21 |
30 | Charter In | RCL | GREEN EARTH | GNE | Laemchabang-Ningbo-Shanghai-Shekou-Sihanoukville-Laemchabang | RBC2 | NA | NA | 14 |
31 | Charter In | RCL | GSL MAMITSA | GMS | Mundra-Nhava Sheva-Jebel Ali(T3)-Jebel Ali-UMM QASR-Jebel Ali(T3)-Jebel Ali-Mundra | RWG | NA | NA | 21 |
32 | Charter In | RCL | LITTLE WARRIOR | LTW | Bangkok(PAT)-Bangkok(SSW)-Laemchabang-Vietnam(CLI)-Ningbo-Shanghai-Laemchabang-Bangkok(PAT) | RBC13 | NA | NA | 21 |
33 | Charter In | RCL | MTT SAISUNEE | MSE | Vietnam(C8Q)-Portklang(Wp)-Kolkata-Kattupalli-Vietnam(C8Q) | RCH9 | NA | NA | 28 |
34 | Charter In | RCL | PALAWAN | PLW | Portklang(Wp)-Vietnam(CLI)-Portklang(Wp)-Jakarta-Portklang(Wp) | RVI | NA | NA | 14 |
35 | Charter In | RCL | TB JINJIANG | TJJ | Mundra-Nhava Sheva-Jebel Ali(T3)-Jebel Ali-UMM QASR-Jebel Ali(T3)-Jebel Ali-Mundra | RWG | NA | NA | 21 |
36 | Charter Out | Hapag-Lloyd AG, Hamburg | API BHUM | APB | Gdansk-Gdynia-Bremerhaven-Wilhelmshaven-Gdansk | NA | NA | NA | NA |
37 | Charter Out | Yang Ming | ARAYA BHUM | AYB | Shanghai-Ningbo-Shekou-Singapore-Karachi-Colombo-Shanghai | NA | NA | NA | NA |
38 | Charter Out | SITC | INTRA BHUM | ITB | Haiphong-Qinzhou-Laem Chabang-Sihanoukville-Hochiminh-Xiamen-Osaka-Kobe-Ningbo-Shanghai-Haiphong | NA | NA | NA | NA |
39 | Charter Out | Pan Continental Shipping | ISARA BHUM | ISB | Incheon-Ningbo-Shanghai-Incheon | NA | NA | NA | NA |
40 | Charter Out | Pacific International Lines | KOTA SYDNEY | IIB | Tema-Lome-Lagos-Onne-Lagos-Abidjan-Singapore-Tema | NA | NA | NA | NA |
41 | Charter Out | Pacific International Lines | KOTA TEMA | GRB | Qingdao-Shanghai-Ningbo-Nansha-Singapore-Tema | NA | NA | NA | NA |
42 | Charter Out | Ningbo Ocean Shipping | MITRA BHUM | MIB | Zhapu-Ningbo-Nagoya-Tokyo-Yokohama-Zhapu-Ningbo-Shimizu-Tokyo-Yokohama-Zhapu-Ningbo | NA | NA | NA | NA |
43 | Charter Out | Sinotrans | PANJA BHUM | PJB | Shanghai-Osaka-Kobe | NA | YES | NA | NA |
Charter Out | Shanghai Panasia | PANJA BHUM | PJB | Weihai-Yantai-Osaka-Kobe-Weihai | NA | YES | NA | NA | |
44 | Charter Out | Sinotrans | SIRI BHUM | SRB | Shanghai-Hong Kong-Haiphong-Hong Kong-Ningbo-Shanghai | NA | NA | NA | NA |
45 | Charter Out | ZIM Integrated Shipping Services Ltd. | ZIM BANGKOK | ZBK | Panama Canal-Pusan-Yantian-Xiamen-Ningbo-Shanghai-Pusan-Manzanillo | NA | NA | NA | NA |
46 | Charter Out | ZIM Integrated Shipping Services Ltd. | ZIM THAILAND | ZTH | Pusan-Manzanillo-Panama Canal-Kingston-Savannah-Charleston-Norfolk-Kingston-Panama Canal-Pusan | NA | NA | NA | NA |
Projects Under Construction
Has Projects Under Construction (Y/N)
No
Debentures & Bills of Exchange
Has Debentures (Y/N)
No
Convertible Securities
Has Convertible Securities (Y/N)
No